Rheinmetall Trims 2026 Outlook as Arminius Order Slips, Setting a Lower Bar for Recovery
Published on 11/04/2026 at 22:01 | Editorial boerse-global.de
Rheinmetall has lowered its full-year guidance, and the market's response was swift: the stock fell 5.2%. The revision raises a pointed question for investors — are these merely timing shifts, or the first sign of deeper execution trouble? The answer will determine whether the reduced expectations form a solid base for a rebound.
Revenue is now projected at around EUR 13.2 billion, down from a prior range of EUR 13.7 billion to EUR 14.2 billion. The cut therefore touches more than the scheduling of individual contracts; it also resets the expected trajectory of the business for the current year.
Two Separate Snags Behind the Downgrade
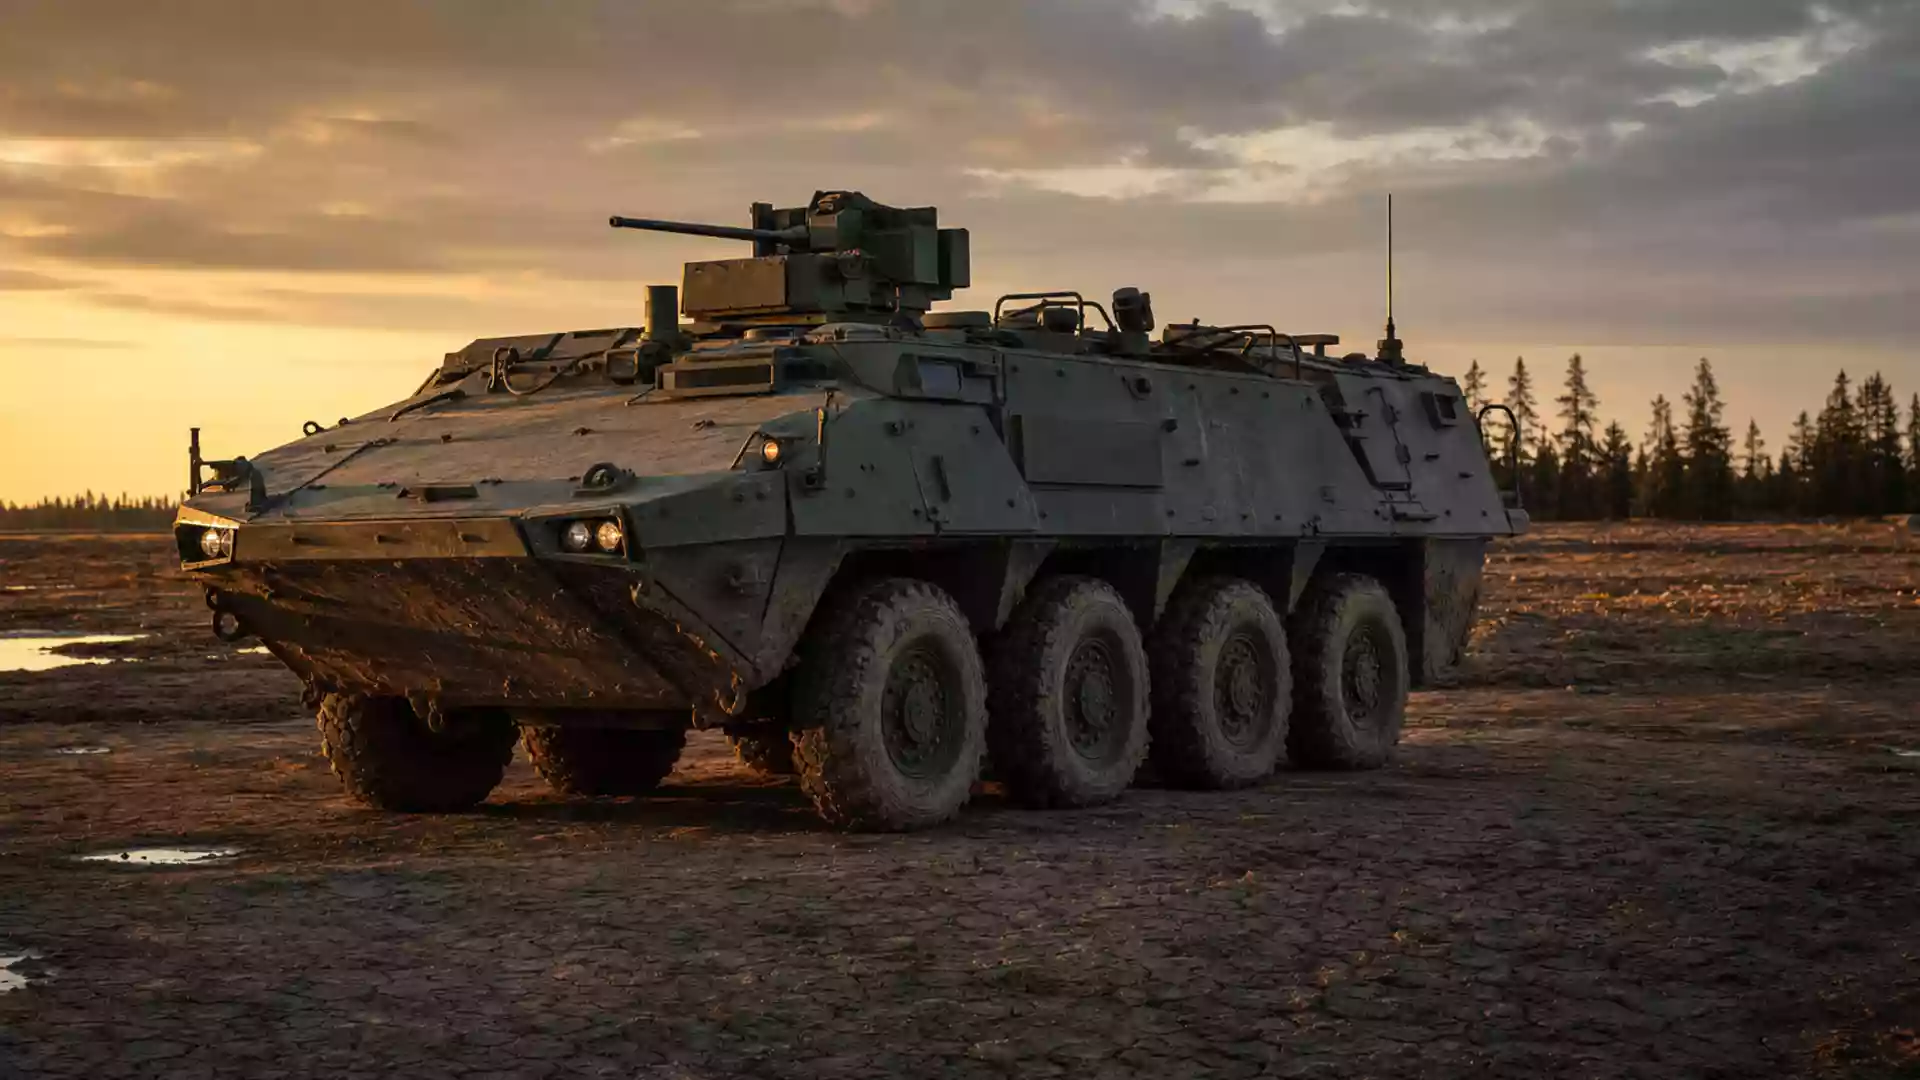
According to a mandatory disclosure, the company no longer expects the order intake for the Boxer project "Arminius" this year. Separately, lot acceptances for artillery ammunition are likely to slip into the following year. These are distinct events — one concerns the awarding of a contract, the other the acceptance of deliveries — and investors tracking a recovery will need to watch both.
The decisive metric is the operating margin. Rheinmetall now expects around 18.5% for 2026, against roughly 19% previously. Alongside the revenue target, expected profitability has come down. Simply catching up on deferred sales would not, on its own, settle the questions around earnings.
What the Third Quarter Actually Delivered
Hard numbers for the third quarter of 2026 show revenue of EUR 3.149 billion and operating profit of EUR 553 million. Those figures describe the business as achieved — they do not guarantee that Rheinmetall meets its new full-year plan. The operating margin for the quarter came in at 17.5%, with order intake reaching EUR 2.893 billion.
Should investors sell immediately? Or is it worth buying Rheinmetall?
Analysts polled by media outlets had, on average, expected revenue of EUR 3.25 billion and operating profit of EUR 531 million ahead of the release. The full quarterly statement, scheduled for 5 November 2026 at 7:30 a.m., should offer further context.
A Fresh Order Adds Some Ballast
On 29 October, OCCAR commissioned Artec — the joint venture of Rheinmetall and KNDS Deutschland — with a further 69 wheeled armored vehicles. Rheinmetall put the value of its share in the mid-three-digit millions of euros. The contract replaces neither the outstanding Boxer award nor the deferred ammunition acceptances, but it illustrates why valuing the company solely on the delayed flagship project would fall short.
Manufacturing news has also moved forward. On 22 October, Rheinmetall opened the UK Gun Hall in Telford for the production of large-caliber weapons, and it reported the handover of the first series Caracal vehicles to the German and Dutch armed forces. On the construction site at Kassel-Calden airport, three pieces of construction machinery burned in the night to Friday; police suspected arson and were examining a confession letter published online.
The Cash-Flow Question Analysts Keep Raising
Berenberg reiterated its "Hold" rating with a price target of EUR 1.020 on Wednesday. Analyst George McWhirter warned that a delay to the large Boxer order would jeopardize Rheinmetall's order target for 2026, with missing advance payments potentially weighing on free cash flow by up to around EUR 3 billion. That is a risk assessment, not a reported charge.
The concern follows a report that the German mega-order is now expected to be placed in February 2027 rather than early December as previously anticipated, which could push order intake and advance payments into 2027. Rheinmetall has not confirmed that possible postponement. Jefferies, by contrast, kept its "Buy" rating on Monday ahead of the figures, with an unchanged price target of EUR 1.350. The stock currently trades at EUR 1.006,80.
The Bar Has Been Lowered, Not Cleared
The optimistic case rests on timing. If the announced artillery ammunition revenue is genuinely realized next year, that portion of the guidance cut would amount to a shift rather than a loss — but the expectation of later revenue is not proof of its realization. The reported quarterly results and new orders stand against the delays.
The pessimistic scenario begins where a postponement becomes repeated planning uncertainty. Should awards or acceptances slip again, even the reduced expectation could come under pressure, forcing investors to reassess not just later revenue but the reliability of the schedule itself. Even if deferred business eventually materializes, the timing of actual cash inflows remains central.
As long as the new margin expectation holds and the deferred acceptances can be caught up, a timing shift remains a plausible reading. Add further delays or fresh earnings setbacks, and that explanation loses conviction. The lowered guidance is a new benchmark, not evidence that difficulties have been overcome. Beyond the quarterly statement, Rheinmetall has slated a Capital Markets Day for 26 November 2026.
Ad
Rheinmetall Stock: New Analysis - 4 November
Fresh Rheinmetall information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.