
Rheinmetall's Cash Flow Warning Casts Shadow Over Record Order Book
Published on 09/24/2026 at 08:51 | Editorial boerse-global.de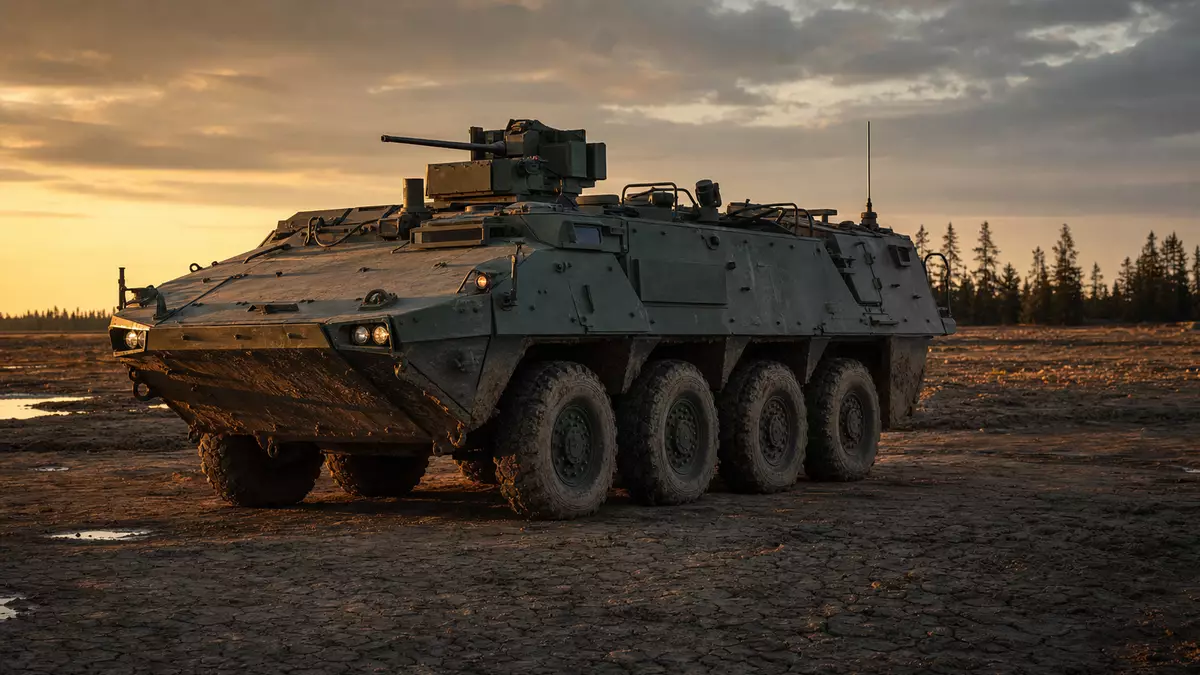
Rheinmetall has spent recent weeks stacking up fresh contracts across its naval, training, and industrial divisions, yet the Düsseldorf-based defence group's decision to flag a sharply negative operating free cash flow for the full year has become the dominant theme for investors. The stock closed yesterday at €1,021.80, up 2.7% on the session, but remains down 34% since the start of the year.
A pivot from expansion to cash discipline
The revised annual targets mark a turning point after months of rapid growth. Management now expects operating free cash flow to land in negative territory for the full year — a shift that has reframed how the market assesses the company's breakneck revenue trajectory.
The warning follows an already telling second quarter, when Rheinmetall booked a 69% jump in revenue to €3,289 million and an operating result of €562 million, yet still posted a clearly negative operating free cash flow. Heavy advance payments for raw materials, the build-up of safety stock, and pre-financing obligations have weighed heavily on liquidity. Whether the group can halt that outflow and convert it into measurable cash generation is now the central question for shareholders.
Order book provides a cushion
The bull case rests on demand that shows no sign of cooling. Rheinmetall ended the second quarter with an order backlog exceeding €80 billion, a level of visibility that has few parallels in European industry. High-margin segments are running at full tilt, with production already underway and deliveries scheduled for 2027.
Analyst Burgess has pointed to substantial valuation upside even under a worst-case scenario for the munitions business, putting a fair-value estimate at €1,450. If Rheinmetall can stabilise its supply chains and execute deliveries as planned, the operating margin — 17.1% in the second quarter — should underpin future earnings growth.
Should investors sell immediately? Or is it worth buying Rheinmetall?
Fresh contracts keep coming
Operational momentum has not stalled. Earlier this month, the company announced a major order for 155-mm artillery ammunition from an international customer, covering a low five-figure unit volume with a contract value in the low triple-digit million euro range and delivery set for 2027.
On the maritime side, Rheinmetall secured a maintenance contract for four new customs vessels powered by liquefied natural gas, deepening its recurring service business in the public-sector segment beyond new-build manufacturing. The group also tested networked unmanned systems on Monday as part of the REPMUS26 exercise, putting new technologies through their paces for harbour protection and the safeguarding of critical maritime infrastructure — a capability drawing growing interest as European states sharpen their security priorities.
In the industrial arena, subsidiary Pierburg Pump Technology received a funding commitment of roughly €1.5 million on Tuesday. The money supports innovative production of NanoLam capacitors, a project carrying total investment of more than €4.4 million.
Execution risks cloud the picture
Against these gains stand concrete operational hurdles. Media reports point to delivery delays on the Boxer wheeled armoured vehicle and the Skyranger air-defence system, while accounts of possible quality defects in protective plating have added to unease. Delays on projects of this scale bring the risk of contractual penalties and costly rework.
Compounding matters, the Bundeswehr's cancellation of the F126 frigate programme — a Rheinmetall project — represents a tangible drag on the annual forecast. Such cutbacks make clear that state procurement plans, however strong the broader rearmament trend, remain exposed to political and budgetary shifts. Should production friction persist, further adjustments to the target corridor cannot be ruled out.
What technicals and the next report will reveal
Market scepticism is visible in the chart: the shares currently trade 25% below their 200-day moving average. As long as the stock defends the support zone established above the round €1,000 mark, the prospect of a bottoming-out stays alive. Timely project completions that restore confidence would open room for a recovery toward medium-term averages. A further wave of bad news on delays, or runaway upfront costs, would instead risk another test of the year's lows.
The next quarterly report is the key catalyst. It will show how severe the cash outflow actually was in the third quarter — and whether the reduced revenue range for 2026 still holds.
Ad
Rheinmetall Stock: New Analysis - 24 September
Fresh Rheinmetall information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


