
Rheinmetall's €80 Billion Backlog Meets a Market That Wants Delivery, Not Deals
Published on 09/25/2026 at 09:30 | Editorial boerse-global.de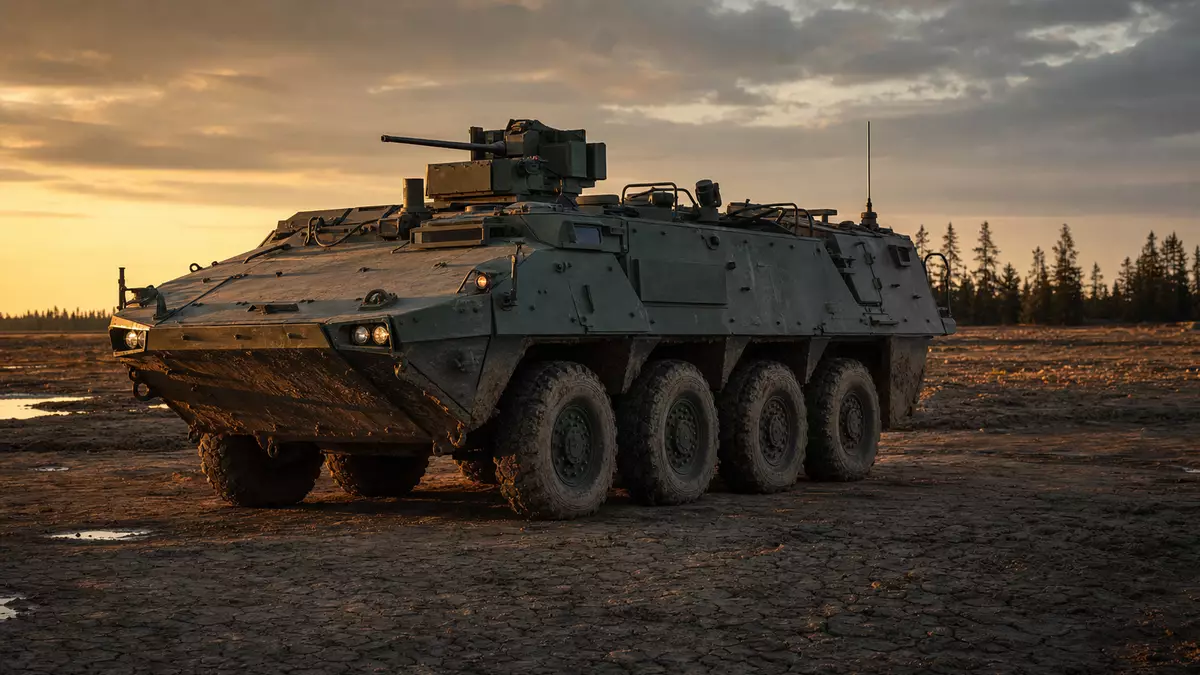
Rheinmetall shares are finding no traction from fresh contract wins, and the reason has little to do with geopolitics. The stock slipped 2.9% in the previous session to close at €992.90, leaving it pinned below the psychologically charged €1,000 line that has repeatedly acted as a battleground in recent trading days. Pre-market indications put the equity at €994.90, still short of that round-number threshold.
The muted reaction to new orders reflects a shift in how investors are pricing the defense contractor. MWB Research keeps its rating at "Hold," arguing that the steady stream of incoming contracts is already baked into the current valuation. Simply announcing another award no longer moves the needle. What shareholders now want to see is how quickly signed deals convert into actual deliveries and earnings.
A 36% Slide That Rewrote the Story
Since the start of the year, the stock has lost 36% and has halved from its 52-week high of €2,007.00. The paper spent months riding an extraordinary special economic cycle, but the market has turned hypersensitive to every political nuance. The question now is whether the current valuation can withstand the changed conditions.
That question sits atop a more fundamental concern: can the company convert its historic order book into revenue on schedule and at a profit? Order intake alone has stopped serving as a share price catalyst. Instead, execution risk and capital commitment dominate the debate.
Operational Snags Take Center Stage
Media reports point to delivery delays on the wheeled armored vehicle and the Skyranger air-defense system, along with possible quality defects in protective plates. At the same time, CEO Armin Papperger has drawn criticism over halted major projects and a leadership structure built heavily around him.
Should investors sell immediately? Or is it worth buying Rheinmetall?
Adding to the pressure is the expectation of a significantly negative operating free cash flow, driven by postponed advance payments, higher customer receivables and an ongoing inventory build to secure production chains.
The Order Book Still Cuts an Impressive Figure
Against those frictions, the company's operating base remains substantial. The order backlog surpassed €80 billion in the second quarter of 2026, reaching €80.5 billion at the end of June including expected framework contract call-offs. Government spending provides further ballast: Germany plans defense outlays of €108.2 billion for 2026.
Demand for core capabilities shows no sign of cooling. In mid-September, Rheinmetall booked an order for a five-digit number of 155mm artillery shells in the low triple-digit million euro range, to be worked off by the end of 2027. Earlier, at the start of July, it secured a contract for four Skynex air-defense systems worth several hundred million euros, with the first unit due for delivery after 21 months.
First-half 2026 figures underscore the operating momentum: revenue climbed 39% to €5.2 billion, with operating profit rising sharply in tandem.
Where the Risks Bite
The positive scenario faces tangible risks that go well beyond geopolitical speculation. The abrupt halt of the F126 frigate program in early July — with Germany switching to eight MEKO A-200 frigates from thyssenkrupp Marine Systems — illustrated how quickly major projects can go wrong. Rheinmetall acted as lead contractor on the €12.80 billion effort.
Then came the August revision of the 2026 guidance, now pointing to revenue of between €13.70 billion and €14.20 billion. Should the reported delays on land systems such as the Skyranger widen, or additional rework become necessary, further erosion of the operating margin looms. The targeted operating margin of around 19% would come under threat.
Rheinmetall at a turning point? This analysis reveals what investors need to know now.
Meanwhile, the inventory build ties up considerable liquidity. If the cash outflow continues, it could noticeably narrow the balance sheet's room for maneuver and provoke further share price declines.
Two Dates That Could Set the Direction
How the company balances growth investment against cash generation will determine the next leg. As long as support near the 52-week low of €902.50 holds, the chance of stabilization remains intact. If sentiment tips on further operational bad news or persistent delays on key projects, a test of those lows becomes likely.
Investors get clarity on the true state of the supply chains and the financial position on November 5, 2026, when the third-quarter statement is published. A second pivotal milestone follows on December 9, 2026, with the Bundestag vote on the Arminius program. Those two dates will likely decide whether Rheinmetall can halt its downtrend.
The gap between a brimming order book and a hesitant share price captures the changed expectations on the exchange. A full pipeline is now treated as a baseline, not a catalyst. Fresh valuation upside demands flawless project execution — and until that materializes, profit-taking looks set to keep calling the tune.
Ad
Rheinmetall Stock: New Analysis - 25 September
Fresh Rheinmetall information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


