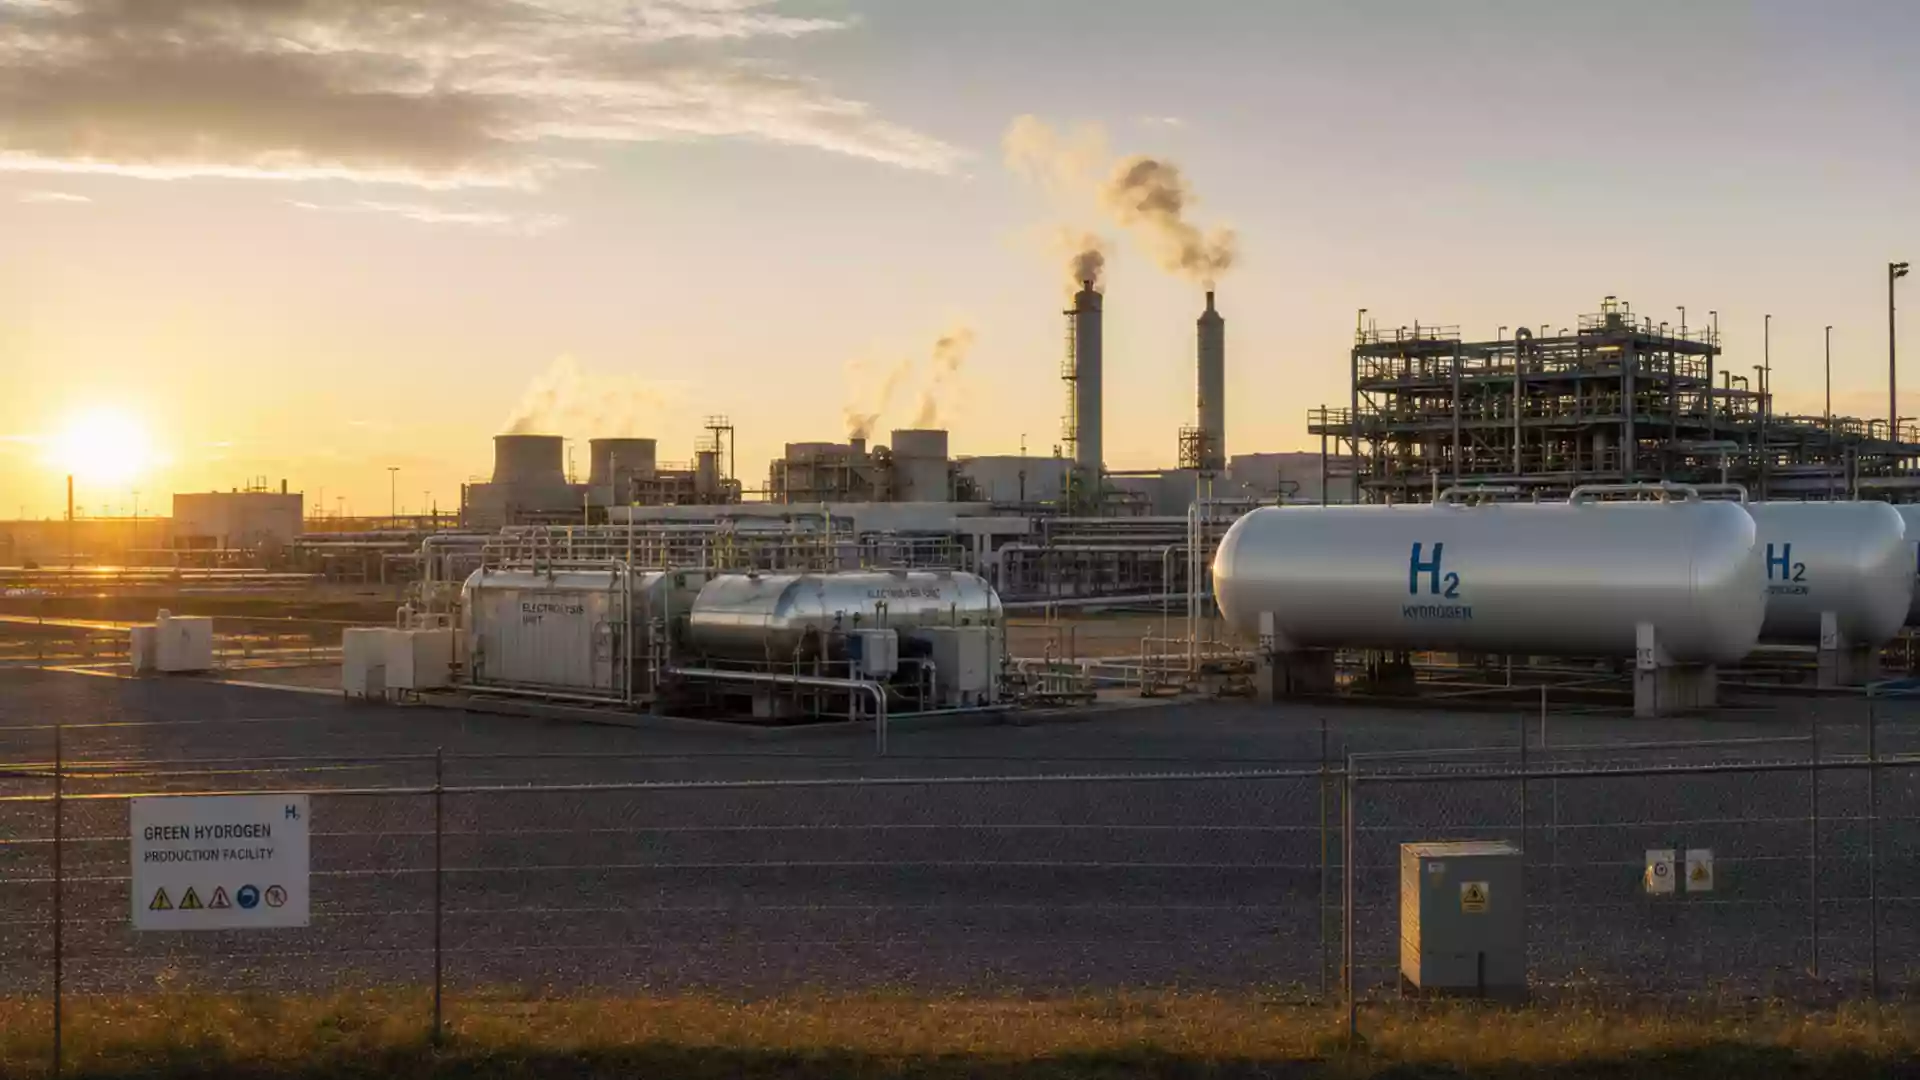
Plug Power's Real Scorecard: $28 Million Out, $134 Million Left, and a November Deadline
Published on 10/31/2026 at 22:30 | Editorial boerse-global.de
Plug Power's shares gave up 3.0% in the previous session, but anyone reading that move as a verdict on the hydrogen specialist is looking in the wrong place. The decline came as U.S. technology names broadly came under pressure from valuation worries and spending concerns tied to artificial intelligence, according to media reports. No causal link between that sector-wide retreat and Plug Power's own business has been established — and a single trading day says nothing about whether the company's growth plans can be financed.
The more useful question sits in the preliminary business update Plug Power issued roughly two weeks ago, and in what it did not say.
Cash Burn Takes Center Stage
Within that release, the company projected a net cash draw of about $28 million for the third quarter of 2026. It put cash and cash equivalents at roughly $134 million at quarter-end, a figure that excludes restricted funds. Both numbers were preliminary and unaudited — a caveat that matters more than it might appear. They offer an initial bearing, not proof of durable financial health, and no single quarter can establish how long the company can keep its spending in check. Extrapolating the cash balance forward would suggest a certainty the disclosure simply does not carry.
What the company did confirm is that it raised no proceeds from its ATM program or from other equity or debt financing during the period. The reported liquidity position therefore stood on its own, unsupported by fresh capital inflows. Plug Power described the net cash use as its lowest to date.
That is a meaningful data point, but it is not evidence that no additional capital will ever be needed. A quarter without financing proceeds and a permanently self-sustaining funding structure are two very different things. For shareholders, the trajectory of operational cash requirements will count for more than the isolated absence of a raise.
Should investors sell immediately? Or is it worth buying Plug Power?
A Manufacturing Mandate, Not a Result
Running alongside the financial test is a personnel move announced around the same time: the appointment of Dr. Lee Sweetland, formerly COO of Ballard Power Systems, as Global Engineering Industrialization Lead. His brief covers the industrialization of PEM stack technology, alongside manufacturing throughput, product reliability and cost competitiveness.
Those are targets, not accomplishments. A hiring decision is an organizational step; it proves neither that costs have already come down nor that reliability has improved. Investors would do well to treat the stated goals as a yardstick for later results rather than as success declared in advance.
Still, the assignment lands on the right pressure point. Growth on its own reveals little about how economically a company delivers its products, and pairing manufacturing execution with cost competitiveness belongs at the heart of the financial test rather than at its technical margins.
Growth Guidance Cuts Both Ways
On the top line, Plug Power guided to revenue growth of more than 10% year over year for the third quarter of 2026 — again part of the preliminary, unaudited update. For the full year, management reiterated its forecast of roughly 15% to 16% revenue growth.
That outlook argues against judging the company on cash consumption alone. By the same token, rising sales should not be mistaken for a return to economic health. The two measures only carry weight in combination.
The company has scheduled its quarterly earnings call for November 9, 2026 — the date on which the preliminary figures will either be confirmed or revised, and the first real checkpoint for the story management has laid out.
Plug Power has identified concrete levers for progress. What it has not yet delivered is proof that revenue growth, manufacturing execution and liquidity discipline can move in the same direction at the same time. Until they do, the financial evidence will carry more weight than any individual growth announcement — and considerably more than a single down day on the tape.
Ad
Plug Power Stock: New Analysis - 31 October
Fresh Plug Power information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.