
Plug Power's New Zealand Electrolyser Ships as COO Exit and Rising Yields Test the Story
Published on 09/25/2026 at 14:20 | Editorial boerse-global.de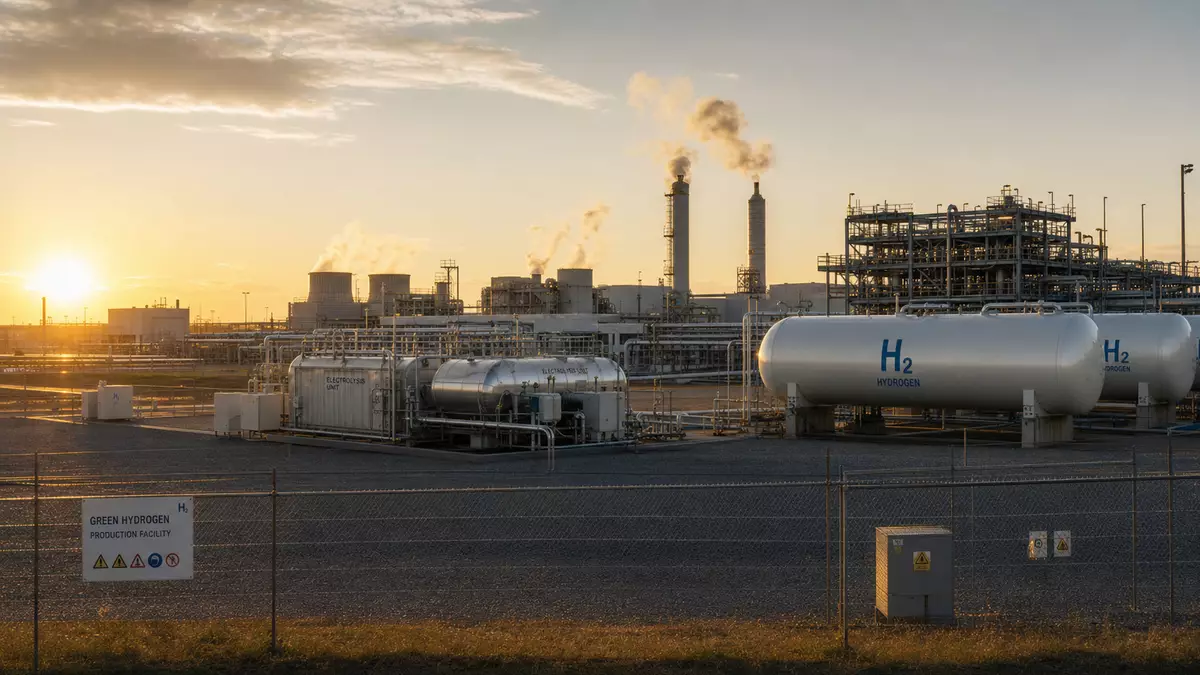
Plug Power's week has been a study in contrasts: a megawatt-class electrolyser left the dock for New Zealand, and the company's chief operating officer handed in his notice. Between those two events sits a stock trading at 1.74 euros, a capital-intensive business model, and a bond market that has stopped being generous.
A Megawatt Heads for Invercargill
On Tuesday, Plug Power shipped a 1-megawatt GenEco PEM electrolyser to its partner HWR Hydrogen in New Zealand. The unit belongs to the renewables arm of the H.W. Richardson Group and is destined for a fueling station in Invercargill, where it will supply green hydrogen to heavy trucks running on a dual hydrogen-diesel drivetrain.
The installation is aimed squarely at decarbonizing road freight, with logistics operators using hydrogen-equipped fleets to test the shift toward lower-emission propulsion. For Plug Power, the export marks the commercial rollout of its electrolyser division in the Pacific region and demonstrates that manufacturing and delivery of the technology can proceed at industrial scale on schedule.
Fullerton's Departure Lands October 23
Against that operational backdrop, the company disclosed a change at the top of its operations. Chief Operating Officer Dean C. Fullerton notified Plug Power on September 17 of his resignation, effective October 23, 2026, to take a position at another company. The mandatory filing states the move did not stem from disagreements with the company, and his duties will be spread across several vice presidents.
Even so, the timing leaves a gap at a moment when production flows and delivery commitments need to run without interruption. A leadership handover raises operational vulnerability precisely when the company can least afford delays, and any slippage in planned projects would further test the market's patience.
Should investors sell immediately? Or is it worth buying Plug Power?
Rising Yields Squeeze the Funding Equation
The broader tape has not been kind. In the previous session, Plug Power shares came under noticeable pressure, falling 3.1 percent to close at 1.74 euros, caught in a broad sell-off across the renewable energy sector. The jump in yields makes borrowing meaningfully more expensive for capital-hungry hydrogen projects, and media reports noted that peers including Bloom Energy and FuelCell Energy also suffered sharp declines.
That headwind arrives at an awkward moment. Plug Power must push ahead with ambitious expansion plans in an already demanding market, and higher rates not only raise the cost of future loans but also dampen the willingness of large prospective customers to commit capital.
Cash Burn Is the Number That Matters
With financing costs climbing, investors are focused on a single existential metric: how quickly operations recover relative to cash consumption. Plug Power has to prove it can scale production profitably before it needs to raise fresh capital.
In the second quarter of 2026, the company burned 61 million dollars. The gross margin did reach breakeven over the same period, but the road to sustainably positive cash flow remains steep. If the capital requirement cannot be covered from its own resources soon, a high-rate environment threatens expensive financing rounds or further dilution for shareholders.
Revenue Beat and Raised Guidance Offer a Counterweight
Operations have provided some arguments for a turnaround. Second-quarter 2026 revenue of 178.3 million dollars beat market expectations, prompting management to lift its annual revenue growth target to 15 to 16 percent. The service and fuel business in particular posted a clear year-over-year margin improvement.
New orders also point to international demand for the company's technology, with the New Zealand shipment serving as the latest example of the systems' practical deployability and underpinning their long-term potential.
Two Paths From Here
The stock currently sits 6.2 percent below its 50-day average of 1.85 euros, and the technical picture offers two clear scenarios. As long as support at the 52-week low of 1.41 euros holds, investors retain the prospect of a gradual bottoming process, and confirmation of the raised growth targets later in the year could ease fundamental pressure.
Should sentiment tip the other way — with bond yields continuing to climb and profitability targets missed — a break below that annual low becomes the risk. The next concrete catalyst is the completion of the operational leadership handover on October 23, 2026, followed by the next set of earnings figures, where the durability of the margin improvement will have to prove itself.
Ad
Plug Power Stock: New Analysis - 25 September
Fresh Plug Power information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


