
Plug Power's New Zealand Electrolyser Deal Lands Alongside Raised Guidance and a Routine Insider Sale
Published on 09/22/2026 at 17:10 | Editorial boerse-global.de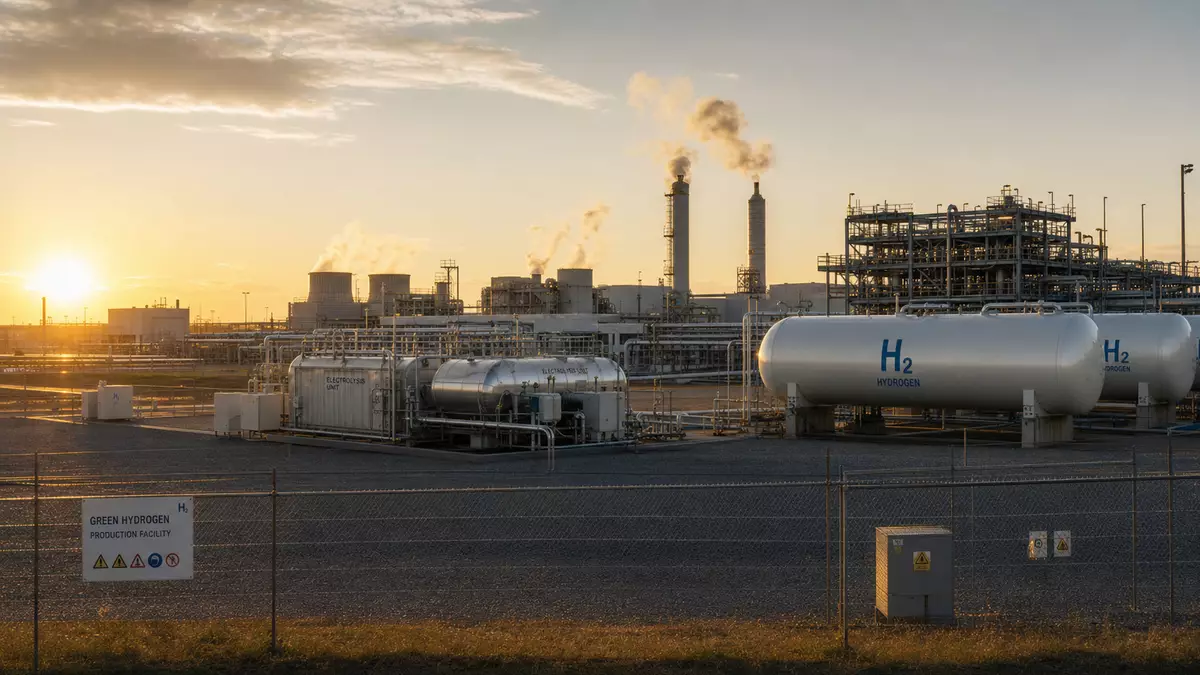
Plug Power has shipped a 1 MW GenEco™ PEM electrolyser to HWR Hydrogen, destined for a hydrogen refuelling station in Invercargill, New Zealand. The delivery extends the US hydrogen group's footprint across both New Zealand and Australia, putting its polymer electrolyte membrane technology to work directly in the transport sector. Regional infrastructure operators are increasingly turning to modular generation capacity to produce green hydrogen right at the pump, and Plug Power sees Australasia as fertile ground for pushing international adoption of its systems.
The timing of the project fits neatly with a broader upgrade to the company's outlook. On 10 August, management lifted its full-year 2026 revenue growth forecast to a range of 15% to 16%. Hitting that target hinges largely on whether planned deliveries of electrolysers and fuel cell systems reach customers in the coming months without delay.
Q4 EBITDAS as the Decisive Milestone
Operationally, the months ahead carry outsized weight. Beyond the top-line guidance, Plug Power is chasing positive EBITDAS in the fourth quarter — a jump in earnings before interest, taxes, depreciation, amortisation and stock-based compensation that stands as the central marker of the ongoing turnaround effort. Getting there will require the company to keep material handling shipments running high and protect margins in the service business.
Should investors sell immediately? Or is it worth buying Plug Power?
Second-quarter figures lend some support to that path. Plug Power shipped 1,666 GenDrive fuel cell systems for material handling, up from 739 units a year earlier — a 125% year-on-year increase. That shipment momentum feeds the downstream service arm: a growing installed vehicle fleet generates recurring maintenance and service revenue, which tends to be more predictable than one-off hardware sales. Service revenue climbed to $29.8 million in the second quarter at a 27% margin, while the fuel business also advanced, lifting revenue by roughly 15%.
Insider Sales Follow a Pre-Set Script
Alongside the operational news, a regulatory filing has drawn attention to share disposals by a senior executive. Benjamin Haycraft, Chief Strategy Officer & General Manager EMEA, parted with 32,560 shares across two transactions in mid-September, executed at $2.14 and $2.06 per share. The sales stem from a Rule 10b5-1 trading plan established on 11 June, which fixes sale timing and conditions in advance. Executives have no say over the precise execution date once such a plan is in motion — a detail that matters for investors, since these disposals run automatically and do not necessarily signal any shift in management's read on the business.
Share Price Holds Its Distance From the Annual Low
In the market, the mixed picture has translated into a tentative stabilisation. Plug Power shares rose 0.8% on the day to €1.84, bringing the year-to-date gain to 9.4%. The prior Monday's close of €1.82 left the stock 29% above its 52-week low of €1.41. Whether the New Zealand push translates into further orders will be decisive for the equipment business going forward, while the planned leap to positive EBITDAS remains the yardstick by which the financial year will ultimately be judged. With summer's growth rates and the raised targets in hand, the course for year-end is set.
Ad
Plug Power Stock: New Analysis - 22 September
Fresh Plug Power information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


