
Plug Power's 2.4-Gigawatt Pipeline Meets a Hard Q4 2026 Deadline
Published on 09/24/2026 at 03:21 | Editorial boerse-global.de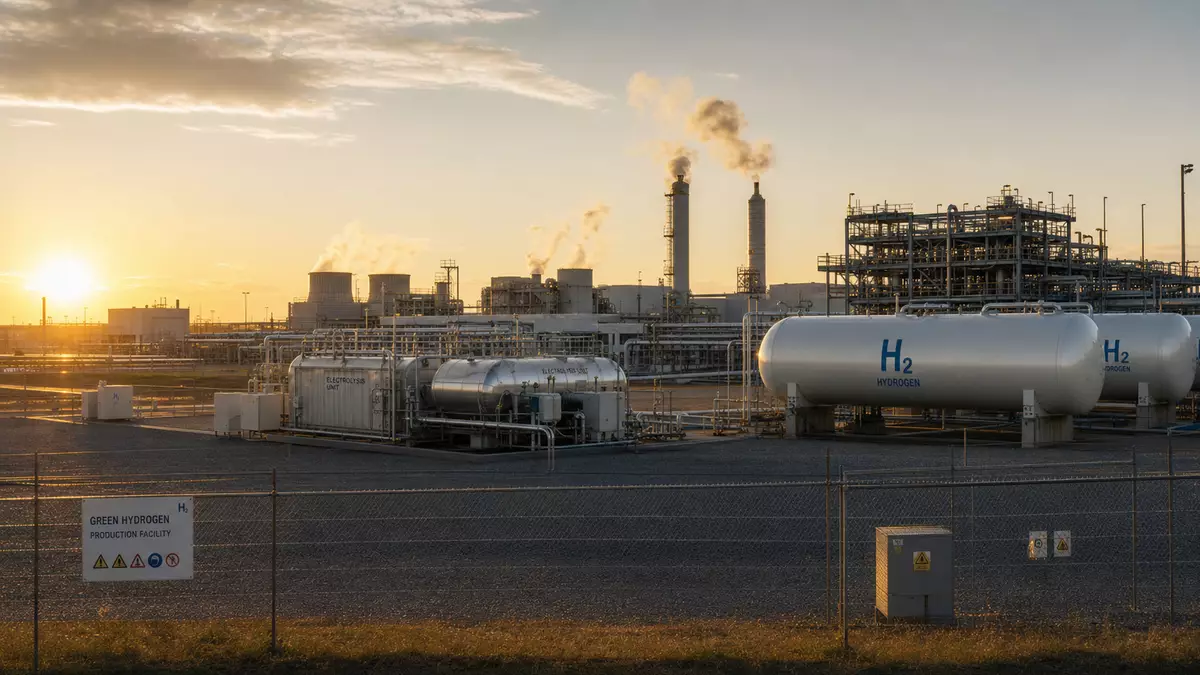
Plug Power has lined up its second major international electrolyser opportunity in barely two months, yet the stock keeps sliding — a disconnect that says as much about investor patience as it does about the company's order book.
Shares of the US hydrogen specialist closed Wednesday at EUR 1.80, down 2.4% on the day. The decline came despite news that Plug Power had shipped a 1-megawatt GenEco PEM electrolyser to HWR Hydrogen for a heavy-duty vehicle refuelling project in New Zealand, a delivery aimed at broadening hydrogen infrastructure across Australasia. A separate trading session saw the stock shed 2.6%, also settling at EUR 1.80. That level sits 28% above the 52-week low of EUR 1.41 touched in March.
A Gigawatt-Scale Consortium Takes Shape in Ningbo
Far larger than the New Zealand shipment is a proposed synthetic aviation fuel complex in Ningbo, where Plug Power is slated to play a central role in plant engineering. The project consortium includes Allied Biofuels, the Sinopec Engineering Group, and technology specialists Topsoe of Denmark and Sasol of South Africa. Sinopec Engineering Group is handling system integration and detailed planning during the pre-engineering phase, with construction to follow.
Plug Power Europe SAS has been designated as supplier of GenEco PEM electrolyser systems, under an arrangement covering a potential total capacity of up to 2.4 gigawatts. The European subsidiary's remit extends beyond the units themselves to basic engineering, technical documentation, and engineering support.
The Ningbo plans follow July's award of a 50-megawatt contract for the Hunter Valley Hydrogen Hub in Australia, giving Plug Power a second international flagship project in quick succession. For a company that reported a modest revenue increase to USD 178.3 million in its most recent quarter alongside a net loss of roughly USD 190.1 million, converting announced megawatt and gigawatt initiatives into billable deliveries has become the central test of management's credibility.
Should investors sell immediately? Or is it worth buying Plug Power?
Why the Market Isn't Cheering
Neither the New Zealand delivery nor the Ningbo consortium has done much to lift sentiment. Investors have moved past announcements and single orders as sources of lasting upside; what they want now is evidence that shipped units can be operated profitably and scaled. With the broader environment for growth-oriented hydrogen equities still strained, every operational step is being weighed against its balance-sheet consequences.
The hesitation extends to the analyst community. UBS rated the stock "Hold" on 16 September 2026, signalling a wait-and-see stance. The final investment decision on the Ningbo project, and the start of construction that would follow, remain the milestones that matter.
One Number Defines the Story: Positive EBITDAS
Management has staked its restructuring narrative on a single target — achieving positive earnings before interest, taxes, depreciation, amortisation and stock-based compensation (EBITDAS) in the fourth quarter of 2026. Missing that mark would erode confidence in the turnaround, and building and delivering electrolysers continues to consume substantial resources. Only when day-to-day operations generate more cash than they burn does reliance on outside capital genuinely recede.
The second quarter of 2026 offered a glimpse of what success could look like. Revenue of USD 178.3 million beat market expectations, and the gross margin improved year over year to roughly breakeven, compared with minus 31% in the prior-year period. Confirmation of that trajectory would show cost reductions are taking hold in operations. Full-year 2026 revenue growth is targeted at 15% to 16%, and the service business and fuel cell unit deliveries have posted clear gains — recurring revenue from those segments could underpin the promised positive quarterly result.
The Cash Burn Still Casts a Long Shadow
Against that optimistic path stands a stark risk case. Net cash outflow in the second quarter was reduced sequentially but still amounted to USD 61 million. Without a further sharp slowdown, the liquidity plan comes under pressure. Delays on major customer projects or supply chain disruptions could stall deliveries once more, and unexpected cost overruns or a missed margin target would raise the odds of additional capital measures — dilution that would weigh heavily on the share price in this environment.
The months ahead amount to a directional verdict for Plug Power. The market wants proof that lower operating expenses haven't come at the cost of long-term delivery capacity, and investors will be scrutinising upcoming quarterly reports for the trend in liquidity reserves and the quality of margins. If the fourth-quarter EBITDAS timeline slips or cash burn accelerates again, further price declines look likely. The next major catalyst is the third-quarter 2026 report, which will show whether the path to the year-end target still holds.
Ad
Plug Power Stock: New Analysis - 24 September
Fresh Plug Power information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


