Intuitive Surgical's Cheaper Instruments Come With a Revenue Trade-Off
Published on 10/21/2026 at 16:20 | Editorial boerse-global.de
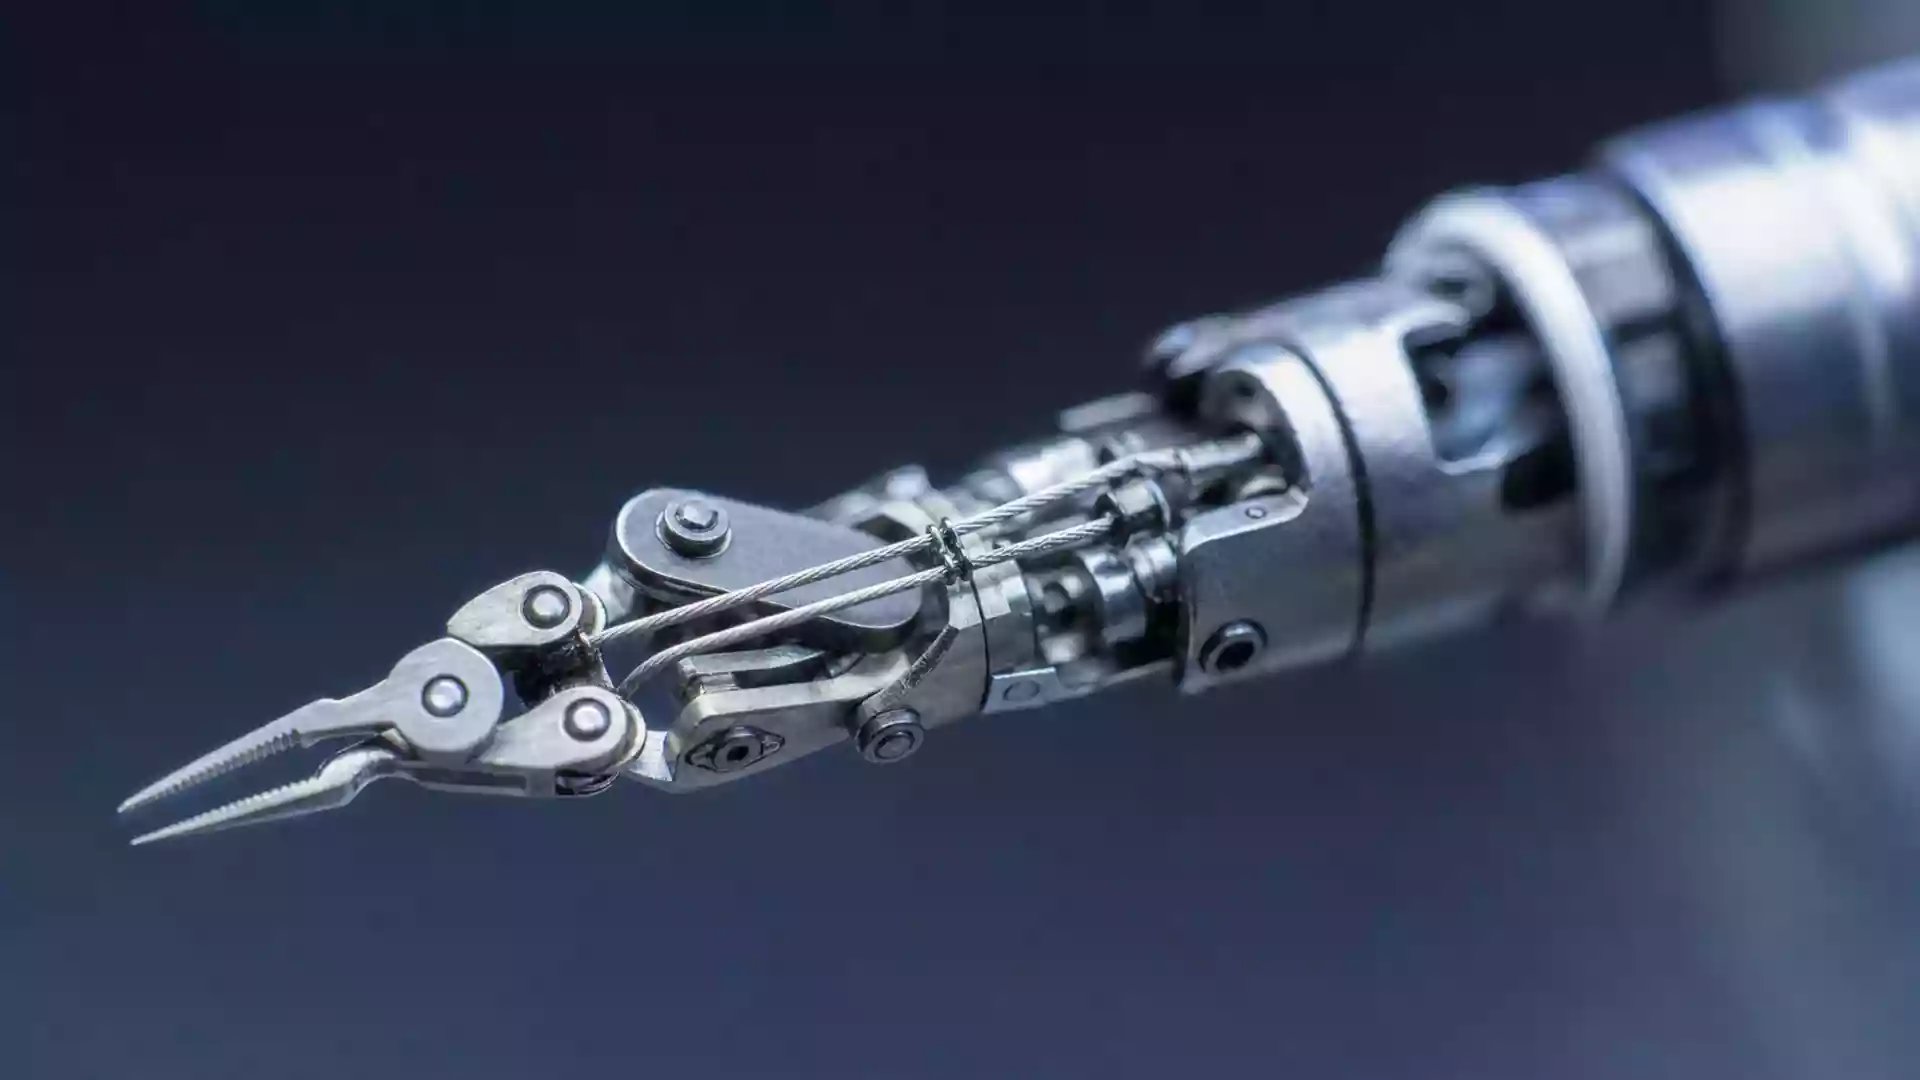
Intuitive Surgical is preparing to make its da Vinci robots less expensive to run. The company plans to cut instrument costs for customers, a move that widens access to its systems but trims the revenue it books on every procedure. Once the measures are fully rolled out, instrument revenue per da Vinci procedure is expected to fall by 3–5% at a constant product mix — a figure that puts pricing, not just procedure volumes, at the center of the investment case.
The centerpiece is the Extended Use Program, which would let customers use instruments longer and thereby lower their costs. According to Reuters, Intuitive intends to launch it first in the US, subject to regulatory clearance — meaning the start date is not yet assured. A price cut in China is slated for November 2026. Finance chief Jamie Samath expects the full effect of the pricing measures to be felt by the end of 2027, so the per-procedure revenue decline is a forward-looking estimate rather than a hit already booked.
That "constant product mix" qualifier matters. The forecast isolates the pricing effect; it does not describe the path of total instrument revenue. Rising procedure counts can offset the drag in principle, though the guidance does not establish whether they will fully cancel it.
The business at stake is far from peripheral. Instruments and accessories generated $1.80 billion in the third quarter of 2026, up 18% year over year. Lower costs for users and lower revenue per case are two sides of the same coin for a segment tied directly to how heavily the installed base is used.
Should investors sell immediately? Or is it worth buying Intuitive Surgical?
A widening gap between home and abroad
Procedure growth in the quarter revealed a sharp regional split. US da Vinci procedures rose 10%, while those outside the US climbed 20%. Worldwide, procedures across da Vinci and Ion together grew roughly 15%, with Ion outpacing da Vinci and system placements continuing.
The softer domestic pace is the number to watch. Samath flagged lower ACA enrollments and changes to Medicaid and the 340B program as risks under observation, and Reuters reported that the lapse of enhanced ACA subsidies has already weighed modestly on US procedure growth.
For 2026, Intuitive narrowed its worldwide da Vinci procedure growth forecast to 14–15%, from an earlier 13.5–15.5% range, and expects results near the midpoint. The revision trims the top of the band while lifting the floor — not a wholesale retreat from its growth expectations.
Two profit figures, one settlement
Reported revenue for the third quarter rose 22% from a year earlier to $3.05 billion. Adjusted diluted earnings per share came in at $3.00, against $1.49 on a GAAP basis. The gap reflects a $450 million pre-tax charge tied to an antitrust settlement.
Intuitive disclosed a written agreement to resolve the class action over its da Vinci surgical robots, comprising a one-time payment and agreed injunctive measures. The company admits neither liability nor wrongdoing, and the settlement still requires preliminary and final court approval. Investors should keep the two earnings figures separate: the adjusted number strips out the charge, while the GAAP figure carries it.
Intuitive Surgical at a turning point? This analysis reveals what investors need to know now.
Margins, tariffs and the analyst split
Guidance for 2026 puts the adjusted gross margin at 68.7%–69.3%, including an estimated tariff hit of 0.9% of revenue and excluding recorded tariff refunds. Growth in adjusted operating expenses is still expected at 11%–13%.
Analysts have not converged on a single read. JPMorgan reiterated its Overweight rating and raised its price target to $475, while Raymond James kept its Outperform rating but trimmed its target to $480. Both houses remain constructive despite the headwinds, yet the divergent target moves show that strong quarterly numbers do not automatically translate into a uniform re-rating.
What ultimately settles the debate is how usage and pricing interact. Intuitive is betting that cheaper instruments and broader access will drive enough additional procedures to absorb the expected per-case revenue decline — and on the regulatory clearances still outstanding for its Extended Use plans.
Ad
Intuitive Surgical Stock: New Analysis - 21 October
Fresh Intuitive Surgical information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.