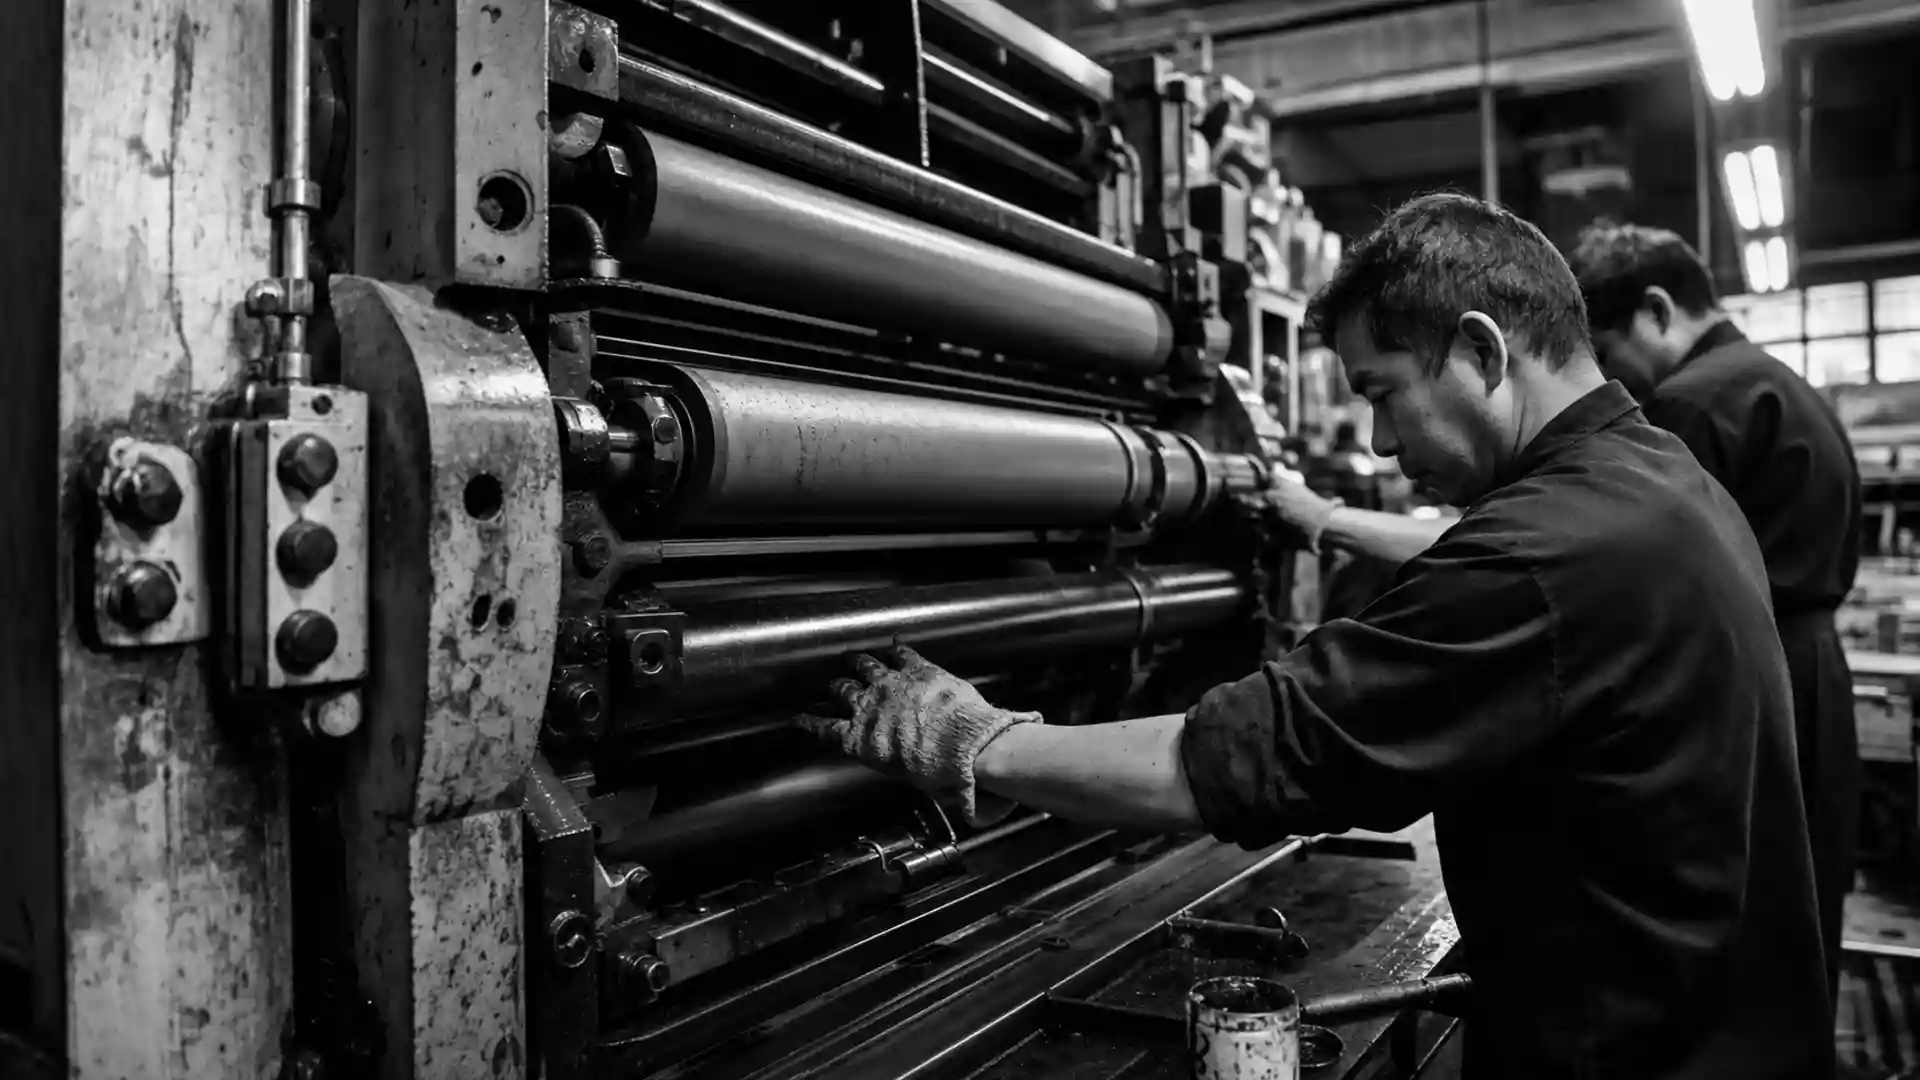
Heidelberg Druck's Order Book Outpaces Revenue as Cash Drain Doubles
Published on 11/14/2026 at 16:41 | Editorial boerse-global.de
Heidelberger Druckmaschinen can point to a healthy pipeline of incoming business. Turning that pipeline into profit and cash is proving to be the harder part.
Shares slipped 3.2% on Friday, a muted reaction that masks a more uncomfortable set of first-half figures published on Thursday. Revenue for the first six months of fiscal 2026/27 came in at EUR 913 million, down from EUR 985 million a year earlier. The adjusted EBITDA margin halved to 3.7% from 6.4%. And free cash flow deteriorated sharply to minus EUR 125 million, compared with minus EUR 64 million in the prior-year period — a cash outflow that roughly doubled.
Orders Outstrip Sales
The order picture offers some encouragement. In the second quarter of fiscal 2026/27, order intake reached EUR 604 million against revenue of EUR 509 million, with an adjusted EBITDA margin of 6.4% for the quarter. That gap between bookings and billed sales is the crux of the investment case: a fuller order book only strengthens the business once those orders are executed at a sufficient margin and ease the strain on liquidity.
Management has pointed to delayed technology projects as a drag, alongside lower volumes, cost pressure and an economic downturn, particularly in the Middle East. Negative product mix effects have added to the squeeze. The combination puts the quality of the business — which orders get processed, and at what cost — squarely in focus.
Should investors sell immediately? Or is it worth buying Heidelberger Druckmaschinen?
Guidance Sets the Bar
Heidelberg reiterated its expectation of stable full-year revenue but trimmed its profitability target, guiding to an adjusted EBITDA margin of 5.6% to 6.6%. That range sits above the first-half level, meaning the company must deliver a markedly stronger second half to land inside it.
For investors, the margin is the more telling test than the top line. Revenue stability earns credibility only if profitability improves alongside it. With weaker volumes and adverse mix effects weighing on margins, the sales target on its own is an incomplete yardstick for a recovery.
Cash Is the Stricter Judge
The doubled cash burn raises the stakes further. A convincing turnaround would need to show up both in the earnings statement and in free cash flow. As long as the liquidity outflow stays elevated, demand alone supports the valuation only to a limited degree.
Two upcoming investor events should shed light on how management intends to close the gap: a Scandinavian roadshow on 16–17 November 2026 and the LBBW German Company Day on 18 November 2026. The most valuable takeaways will concern the named burdens — what progress is being made on delayed projects, costs and product mix, and how orders convert into revenue and ultimately into cash.
The thesis gains conviction if Heidelberg processes its existing demand more profitably and curbs the outflow of funds. That execution, rather than the order intake itself, is what the next round of progress should be judged against.
Ad
Heidelberger Druckmaschinen Stock: New Analysis - 14 November
Fresh Heidelberger Druckmaschinen information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.