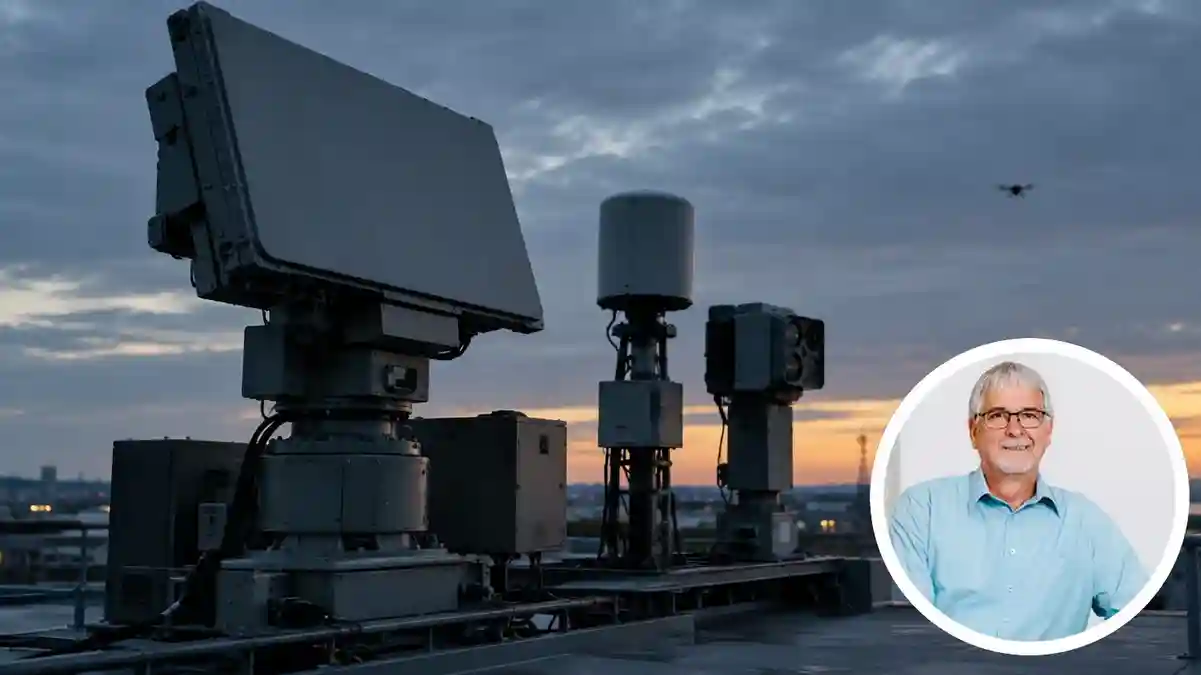
DroneShield's A$125.8 Million Record Sits Beside a A$32.2 Million Loss as ASIC Cloud Lingers
Published on 11/14/2026 at 17:21 | Editorial boerse-global.de
DroneShield shares gave up 4.1% on Thursday as risk aversion swept the ASX, with investors weighing a record top line against a statutory half-year loss of A$32.2 million and the unresolved question of an ongoing ASIC investigation.
The loss and the regulatory uncertainty, rather than any shortage of operational demand, dominated the session. That split — between what the counter-drone specialist can win and what it can keep — has become the central test for the equity.
Committed Revenue Lands Mid-Range
On the commercial side, the company put committed revenue for the 2026 financial year at A$261 million as of October, a figure drawn from its October corporate update. That sits comfortably inside management's guidance range of A$250 million to A$270 million, leaving the committed book roughly in the middle of the band. The read-through published on Tuesday was an analysis of that update.
The record A$125.8 million in revenue shows the demand is real. Whether it converts into a durable business is a separate question, and one the loss line keeps forcing back into view.
Should investors sell immediately? Or is it worth buying DroneShield?
Air Force Seeks the Missing Pieces
A fresh procurement notice added a more granular data point. The U.S. Air Force on Tuesday issued a solicitation for equipment needed to operate DroneShield Immediate Response Kits at Joint Base San Antonio. The tender followed the service's finding that the kits were missing essential components — the purchase covers the supplementary parts required to bring them into service at that location.
Read one way, the notice is a vote of confidence in the hardware. Read another, it is a reminder that fielding a system involves more than shipping a box.
A Dutch Shortlist and a Doctrine Argument
DroneShield also counts among the final three contenders in a Dutch counter-drone competition, according to media reports — the same coverage that flagged the Air Force solicitation. Separately, strategic adviser David Doran made the case on Tuesday, in an opinion piece, for stronger counter-drone capabilities within the U.S. National Guard, framing the gap as a capability requirement.
DroneShield at a turning point? This analysis reveals what investors need to know now.
DroneShield itself set out a broader definition of effective counter-drone work on 8 November. In the company's telling, planning, operator training, continuous learning and software updates matter as much as the equipment itself. That framing puts execution — and the economics of delivering it — at the heart of the investment case.
For now, the stock's direction hangs on a plain question: can operational relevance be turned into a profitable business? The tenders and shortlists offer concrete footholds. Until the losses narrow and the ASIC matter clears, conviction is likely to stay pinned to that answer.
Ad
DroneShield Stock: New Analysis - 14 November
Fresh DroneShield information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.