ASML Wins Twin Bull Calls as High-NA Reliability Takes Centre Stage
Published on 11/19/2026 at 21:11 | Editorial boerse-global.de
Goldman Sachs added ASML Holding to its conviction list on Wednesday, reaffirming a buy rating and a twelve-month price target of EUR 2,315 following a visit to the company's Wilton facility. The endorsement lands alongside a fresh buy call from Bernstein, which reiterated its own recommendation a day earlier with a target of EUR 2,500.
The stock climbed 3.4% as European semiconductor names recovered, with Reuters also reporting gains at STMicroelectronics and Infineon. Notably, the advance came without any announcement of a new equipment order or a revised company forecast.
Tool uptime becomes the metric to watch
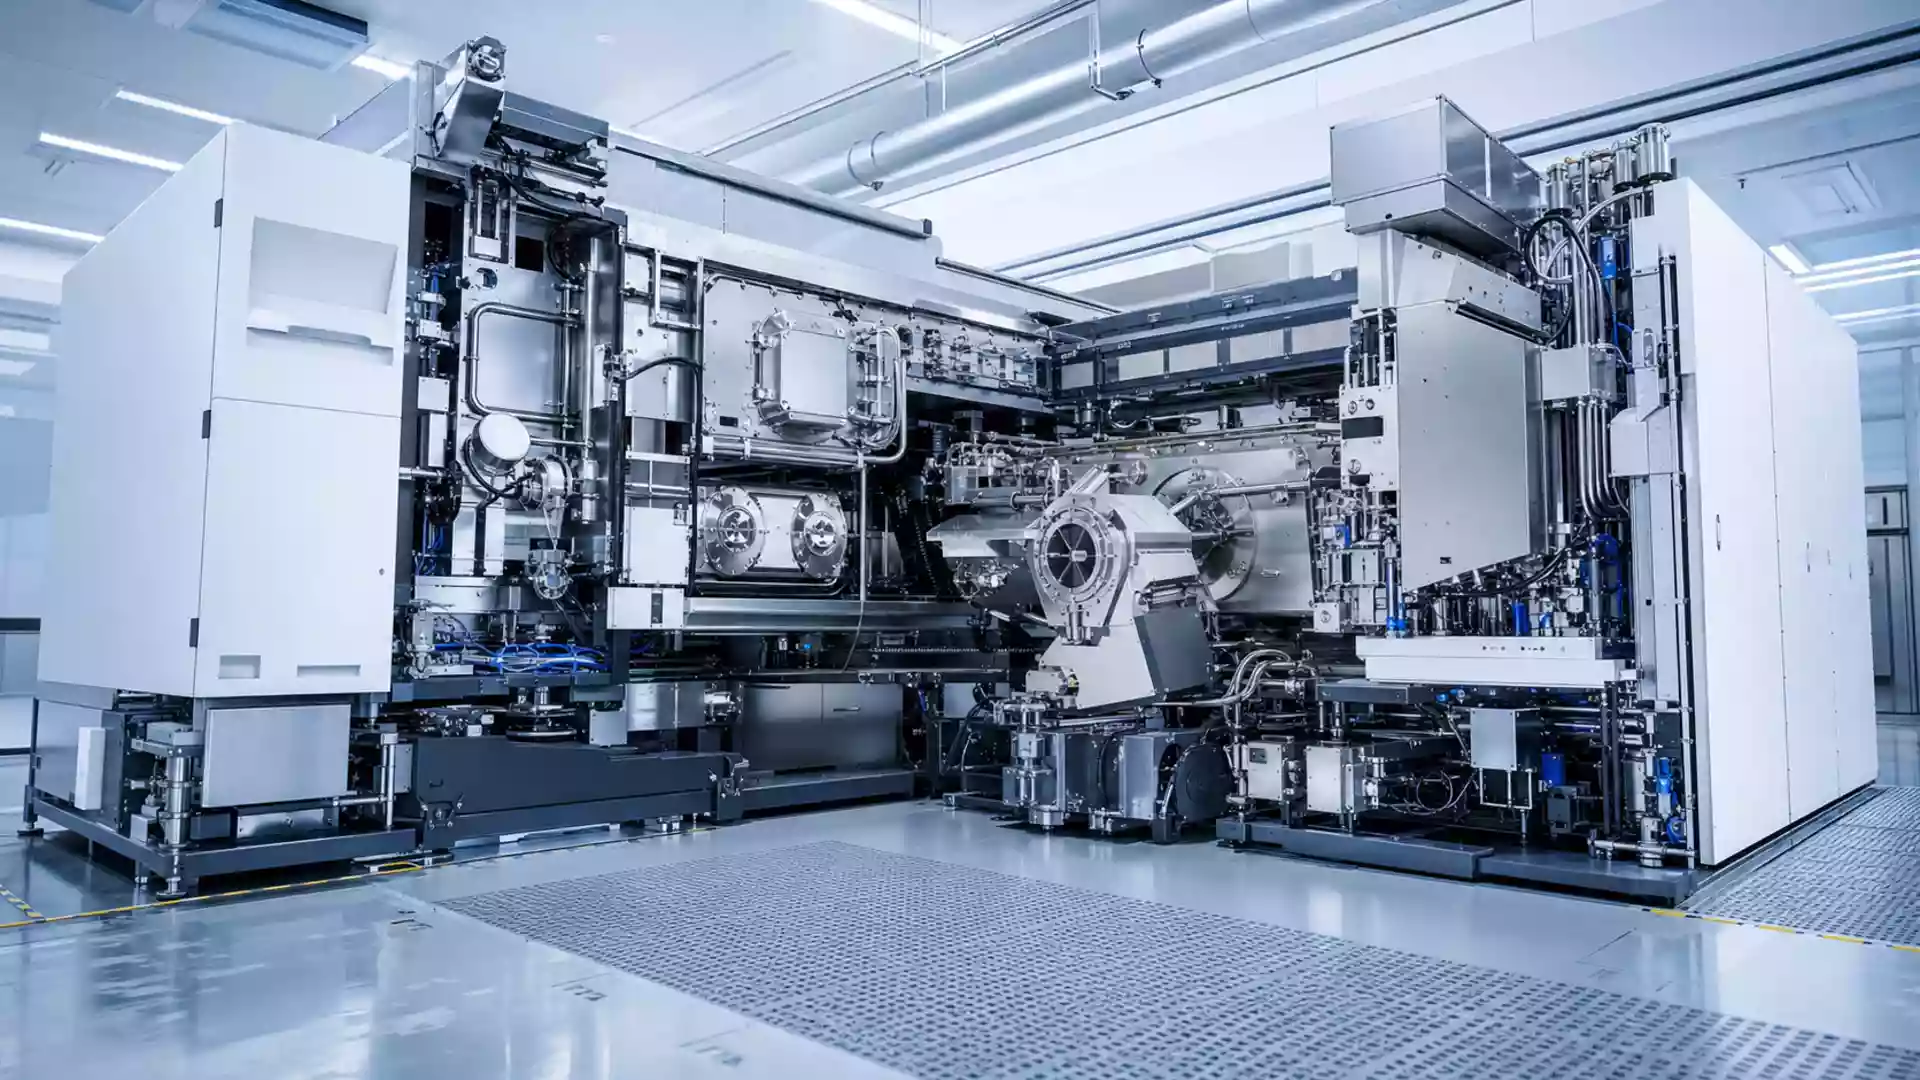
What separates the Goldman thesis from a simple demand story is its focus on execution. The bank puts availability across ASML's High-NA lithography fleet at 87%, against a year-end target of 90%. On that reading, the investment case rests as much on how reliably installed systems run as on appetite for new ones.
Capacity is the other half of the equation. ASML has restated its expansion plans, yet chief executive Christophe Fouquet has indicated that planned delivery volumes are unlikely to fully meet customer demand in either of the coming two years. Clients have also signalled interest in booking equipment for 2029 and 2030 — enquiries that fall short of firm orders, though management considers its planned capacity potentially insufficient and is weighing a further build-out beyond 2028.
Should investors sell immediately? Or is it worth buying ASML Holding?
Spending forecasts underpin the bull case
Bernstein's numbers sketch the scale of the opportunity. The brokerage sees worldwide wafer fabrication equipment spending reaching USD 156 billion in 2026 and USD 217 billion in 2027.
ASML's own guidance, issued on 14 October, points to full-year 2026 revenue of EUR 44 billion to EUR 45 billion at a gross margin of roughly 56%. For the third quarter of 2026, the company reported net sales of EUR 11.662 billion and net profit of EUR 4.960 billion. It remains the only commercial supplier of EUV lithography systems worldwide.
China and delivery risk in the balance
Roughly 20% of 2026 revenue is expected to come from China, according to management estimates. Goldman anticipates that any additional export restrictions would have a material effect no earlier than 2028. The bank also flags delays in EUV shipments, swings in the investment cycle and market-share losses as risks alongside export policy.
For investors, the two recommendations ultimately hinge on separate questions: whether chipmakers convert their investment plans into binding orders, and whether ASML can ship its systems on schedule. Demand alone would not offset potential delivery slippage — which is why the reliability of the installed fleet has moved to the centre of the Goldman case.
Ad
ASML Holding Stock: New Analysis - 19 November
Fresh ASML Holding information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.