Almonty: Two Targets Cut, One Ship Booked, and a Tungsten Price That Keeps Slipping
Published on 10/22/2026 at 16:41 | Editorial boerse-global.de
Almonty's tungsten mine at Sangdong is moving forward on the ground. The market, meanwhile, is marking the stock down — and the reasons are not all about the mine. On Tuesday, Oppenheimer trimmed its price target on the tungsten producer from US$25 to US$19 while keeping its positive rating, according to media reports. The cut came on the eve of the company's investor day and rested on two separate levers: lower valuation multiples among comparable companies, and softening tungsten and APT prices.
That distinction matters. A commodity market shapes the economics of a project; a peer multiple shapes the yardstick investors apply to the share price. Both can pull a target lower even when the underlying business is advancing. Oppenheimer's move illustrates the split neatly — conviction in the company and caution on the right price for its stock can coexist.
Stifel Follows With a Smaller Cut
Oppenheimer was not alone. Stifel's analysis on Tuesday lowered its own Almonty target from US$25 to US$21, holding its buy recommendation. The driver here was different: revised delivery assumptions for the first and second phases of Sangdong, made after the investor day. Stifel described the event as free of groundbreaking news.
The pattern across the two houses is the same — expectations adjusted, enthusiasm retained. Neither analyst abandoned the investment case; both reworked the numbers that feed into it. Production progress, in other words, does not automatically offset more cautious shipping assumptions.
A Mine That Is Running, a Cargo That Has Not Sailed
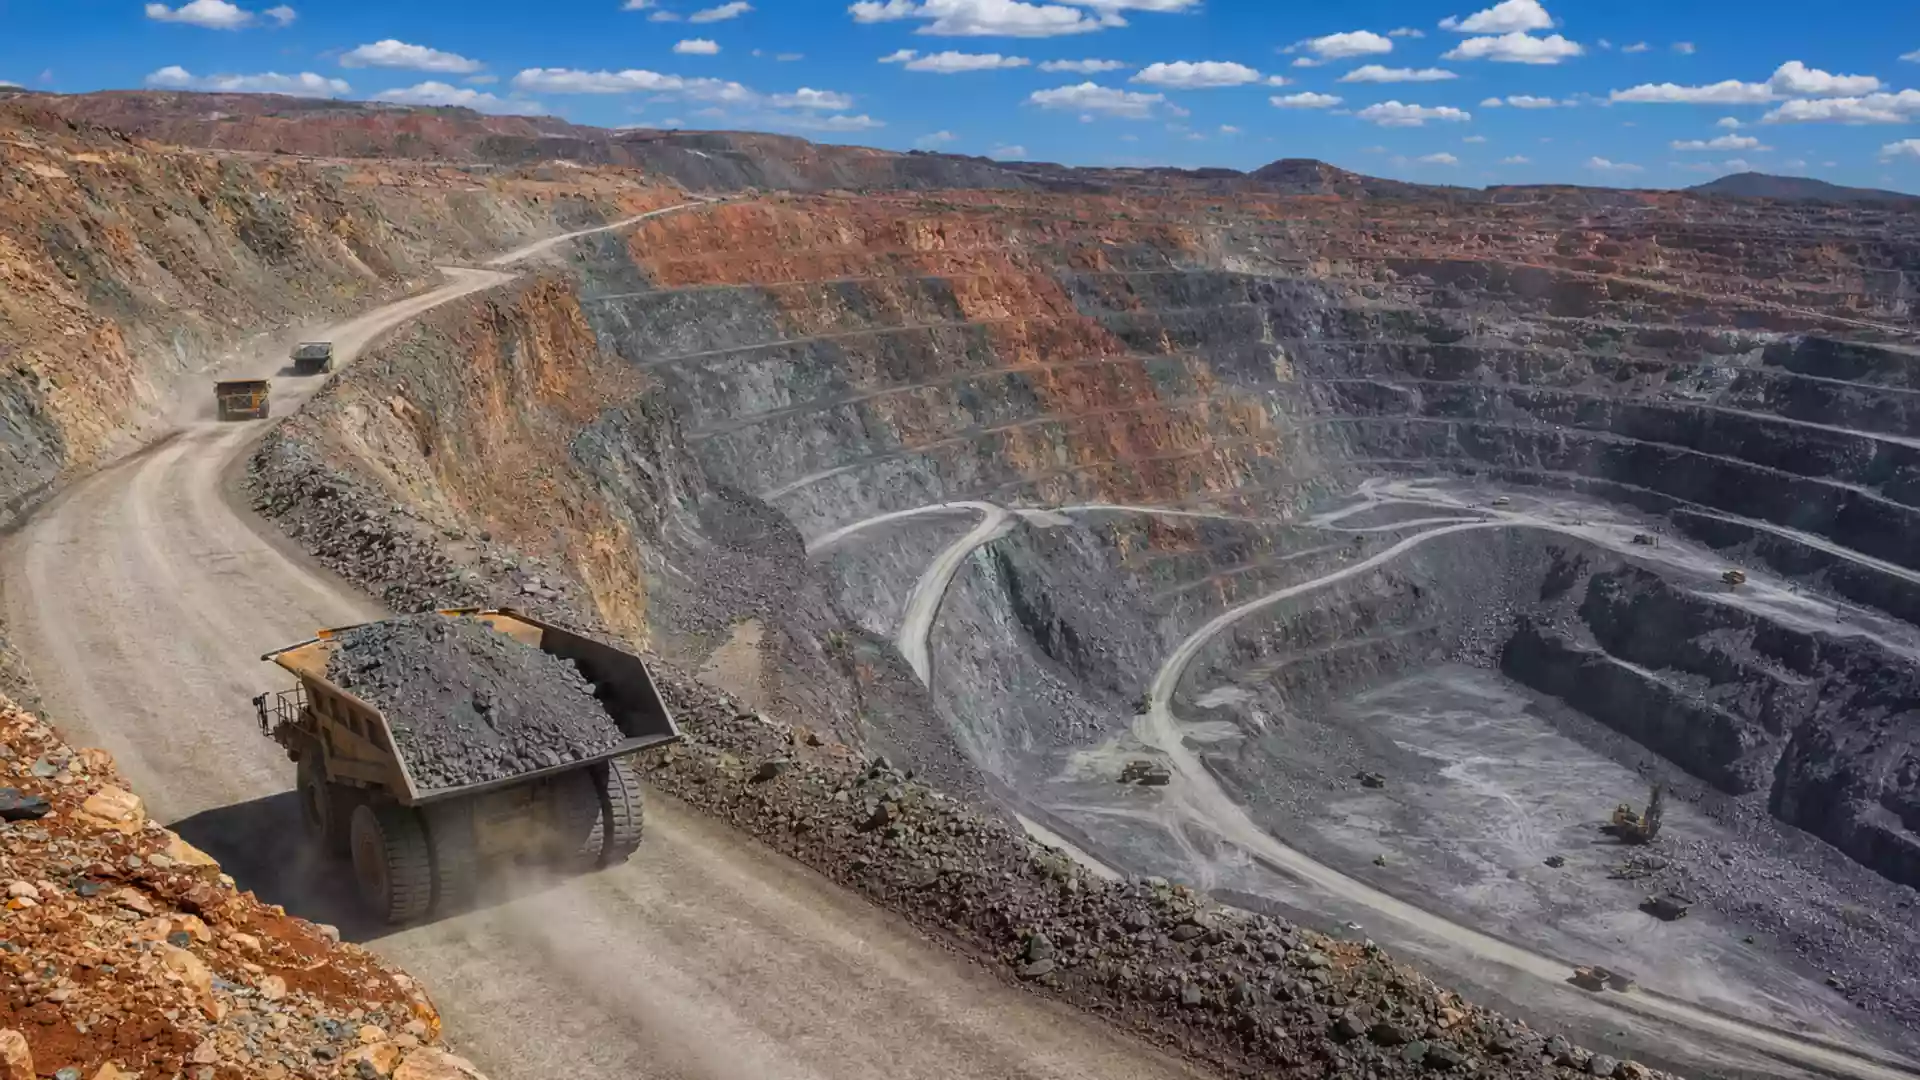
On the operational side, Diamond Equity Research reported yesterday that Sangdong has begun producing tungsten concentrate. That is a genuine step forward, but it answers a different question from the one investors ultimately care about: produced concentrate and delivered tonnage are not the same thing.
Should investors sell immediately? Or is it worth buying Almonty?
For the first shipment, announced roughly two weeks ago, a vessel has been booked for 24 October 2026, according to the same report. A booking describes a planned transport step, not a completed delivery. It does put a concrete date on the calendar against which the next stage of expectations can be measured.
The second expansion phase is already underway, with completion targeted for 2027. That remains a future goal. Production start, shipment and expansion are three separate things to judge, even though they belong to the same project.
The Price Headwind Behind the Story
Raw-material prices have deteriorated alongside the delivery revisions. Shanghai Metals Market reported a reference price for wolfite concentrate of RMB 302,000 per standard tonne as of 15 October — a drop of RMB 75,000 per standard tonne within the month. That is an industry-wide move, not a company announcement from Almonty.
The broader tungsten market has been under pressure for longer. On Tuesday, the decline of tungsten prices from their historic highs was put at nearly 70% over seven months. That describes the sector's headwind, though it does not by itself explain every individual move in Almonty's shares.
What the Company Has Said It Will Do
Against that backdrop, Almonty's own plans remain on the table. A company-commissioned analysis pointed to the expected completion of Sangdong's second expansion phase in 2027 and highlighted authorisation for a share buyback of up to US$300 million.
Both deserve careful wording. An expected project completion is not a finished project. A buyback authorisation does not mean the company has already repurchased shares on that scale. And a commissioned report is not the same as an independent analyst decision.
Almonty at a turning point? This analysis reveals what investors need to know now.
Two Brakes, One Stock
The stock has felt the pressure. On Tuesday it showed a daily change of -6.6% at €7.77, while pre-market trading on the following day pointed to a -3.6% move — a shift for which no fresh company-specific trigger could be identified.
Pinning the decline solely on the commodity price would be too tidy a story. Two distinct brakes are at work: softer tungsten prices weighing on economic expectations, and lower peer multiples resetting the valuation benchmark. Delivery assumptions add a third, more company-specific layer.
The takeaway is not whether Almonty can push its projects forward — the evidence suggests it can. The question is under what market conditions those advances translate into economic value, and how the announced project milestones actually convert into shipments.
Ad
Almonty Stock: New Analysis - 22 October
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.