

Almonty Ties Off a Legal Loose End While Sangdong's Ramp-Up Grinds On
Published on 10/12/2026 at 09:10 | Editorial boerse-global.de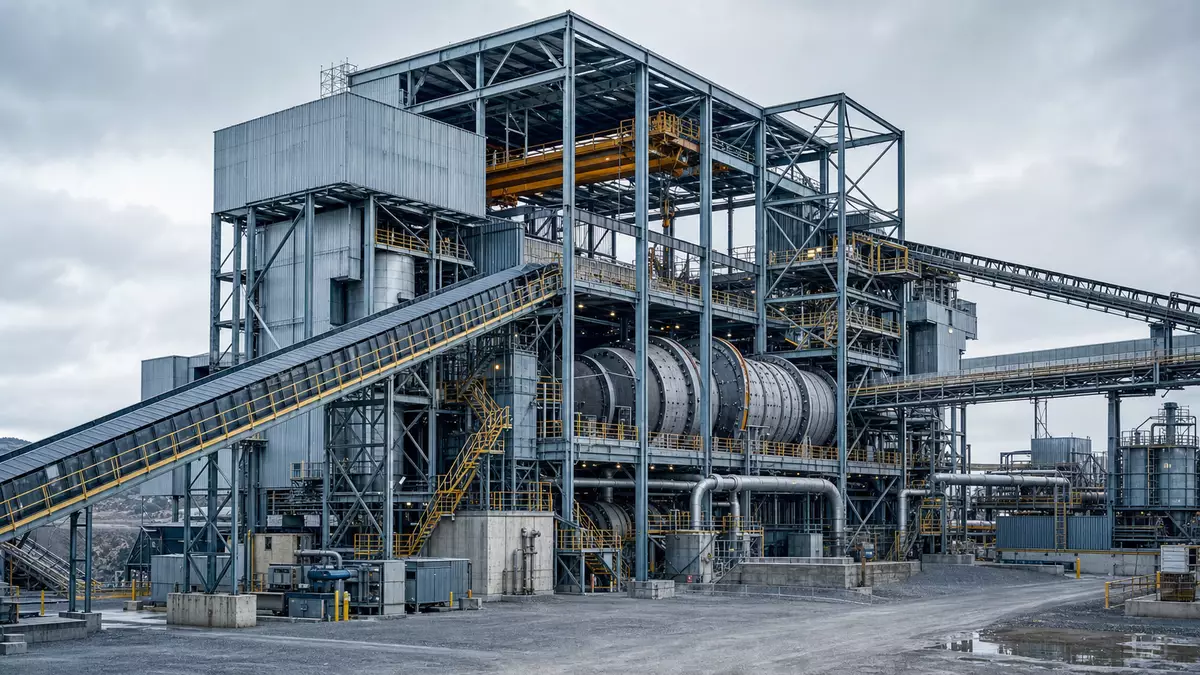
Almonty has closed the book on a dispute over how one former associate's role is described, and the company made clear the resolution says nothing about how its flagship mine is performing. A settlement agreement with Pure Tungsten produced a corrective statement, published on October 2, confirming that Tiger Kim never held an executive, managerial or board position at Almonty. His work as an independent contractor ended on December 31, 2015.
That distinction sits at the heart of the disclosure. Contracting for a company is not the same as running one or sitting on its board, and Almonty's statement draws a line around both the nature and the duration of the earlier relationship. The settlement and the subsequent publication are finished business — the resolution of a disagreement over how a past engagement was portrayed, not a fresh operational milestone for Sangdong.
A Change of Auditor, Minus Any Disagreement
Separately, Almonty reported a switch in its independent registered public accounting firm. PricewaterhouseCoopers LLP took up the mandate on September 29, following the resignation of Zeifmans LLP. The required filing stated that the change stemmed from no disagreement over accounting, disclosure or auditing matters.
That explicit framing matters for shareholders: the auditor transition and the legal clarification are two unrelated items, and neither carries any new information about production volumes or financial results. Both announcements deserve to be weighed apart from the company's operating progress.
Should investors sell immediately? Or is it worth buying Almonty?
Where the Real Story Sits
The operational backdrop comes from a shareholder letter published roughly two weeks ago, in which Almonty reported the start of tungsten concentrate production at Sangdong alongside ongoing underground development work for Phase II. According to media reports, CEO Lewis Black told an audience on Wednesday that he expects orders for the next expansion stage's equipment to be placed within four to six weeks, while pointing to technical fine-tuning during the ramp-up.
Those comments came at the International Investment Forum, where Black described Sangdong as operational and climbing toward full output. The company has also disclosed a damaged pipeline that required replacement lines — a reminder that a running plant is not the same as a plant whose every process meshes reliably. The pipe failure does not undercut the progress made; it illustrates why investors should separate the start of production from a settled, routine operation.
Black's shareholder letter sketched a processing plant running 13 hours a day, seven days a week, with plans to extend that to round-the-clock operation. The first concentrate shipment has been booked for October 24. Each of those data points marks a different stage: the plant is working, hours are set to grow, and the cargo is prepared. A booked shipment, though, remains a booked shipment — it should not be treated in any valuation as a completed delivery ahead of time.
Tailwinds Are Not a Substitute for Execution
A market commentary circulated Wednesday by Western Star cited S&P Global estimates pointing to a potential shortfall of roughly 21,000 tonnes in tungsten supply outside China in 2026. That is a favorable backdrop for Almonty, but it cannot stand in for operational reliability. The scarcity thesis explains why Sangdong's development draws attention; it does not answer how smoothly the company handles its next steps, nor does it establish any proven link to Friday's 2.7% share price gain. No concrete trigger for that move can be extracted from the company's announcements.
Almonty at a turning point? This analysis reveals what investors need to know now.
Which is precisely why the market commentary should not be the lead argument. The stronger case lives inside the company itself: it reports actual operations while naming technical difficulties along the way. That candor is more useful for assessment than a view that highlights only the supportive raw-material environment.
On balance, a cautiously positive read on the operating trajectory holds up. Almonty has reported progress that goes beyond mere planning, yet the rework shows the ramp-up still demands attention. Reliable execution is the yardstick that counts, and the announced next steps offer orientation without counting as results already achieved. The story gains substance when a running operation turns into dependable routine — and the share price gain alone proves none of that yet.
Ad
Almonty Stock: New Analysis - 12 October
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


