Almonty's Sangdong Ramp-Up Is Real; the Earnings Quality Is the Open Question
Published on 11/14/2026 at 06:40 | Editorial boerse-global.de
Almonty shares climbed 8.5% on Friday, but the more instructive story sits behind the ticker: a tungsten producer that has just booked its first concentrate, its first loaded shipment, and a headline profit that owes almost everything to accounting rather than mining.
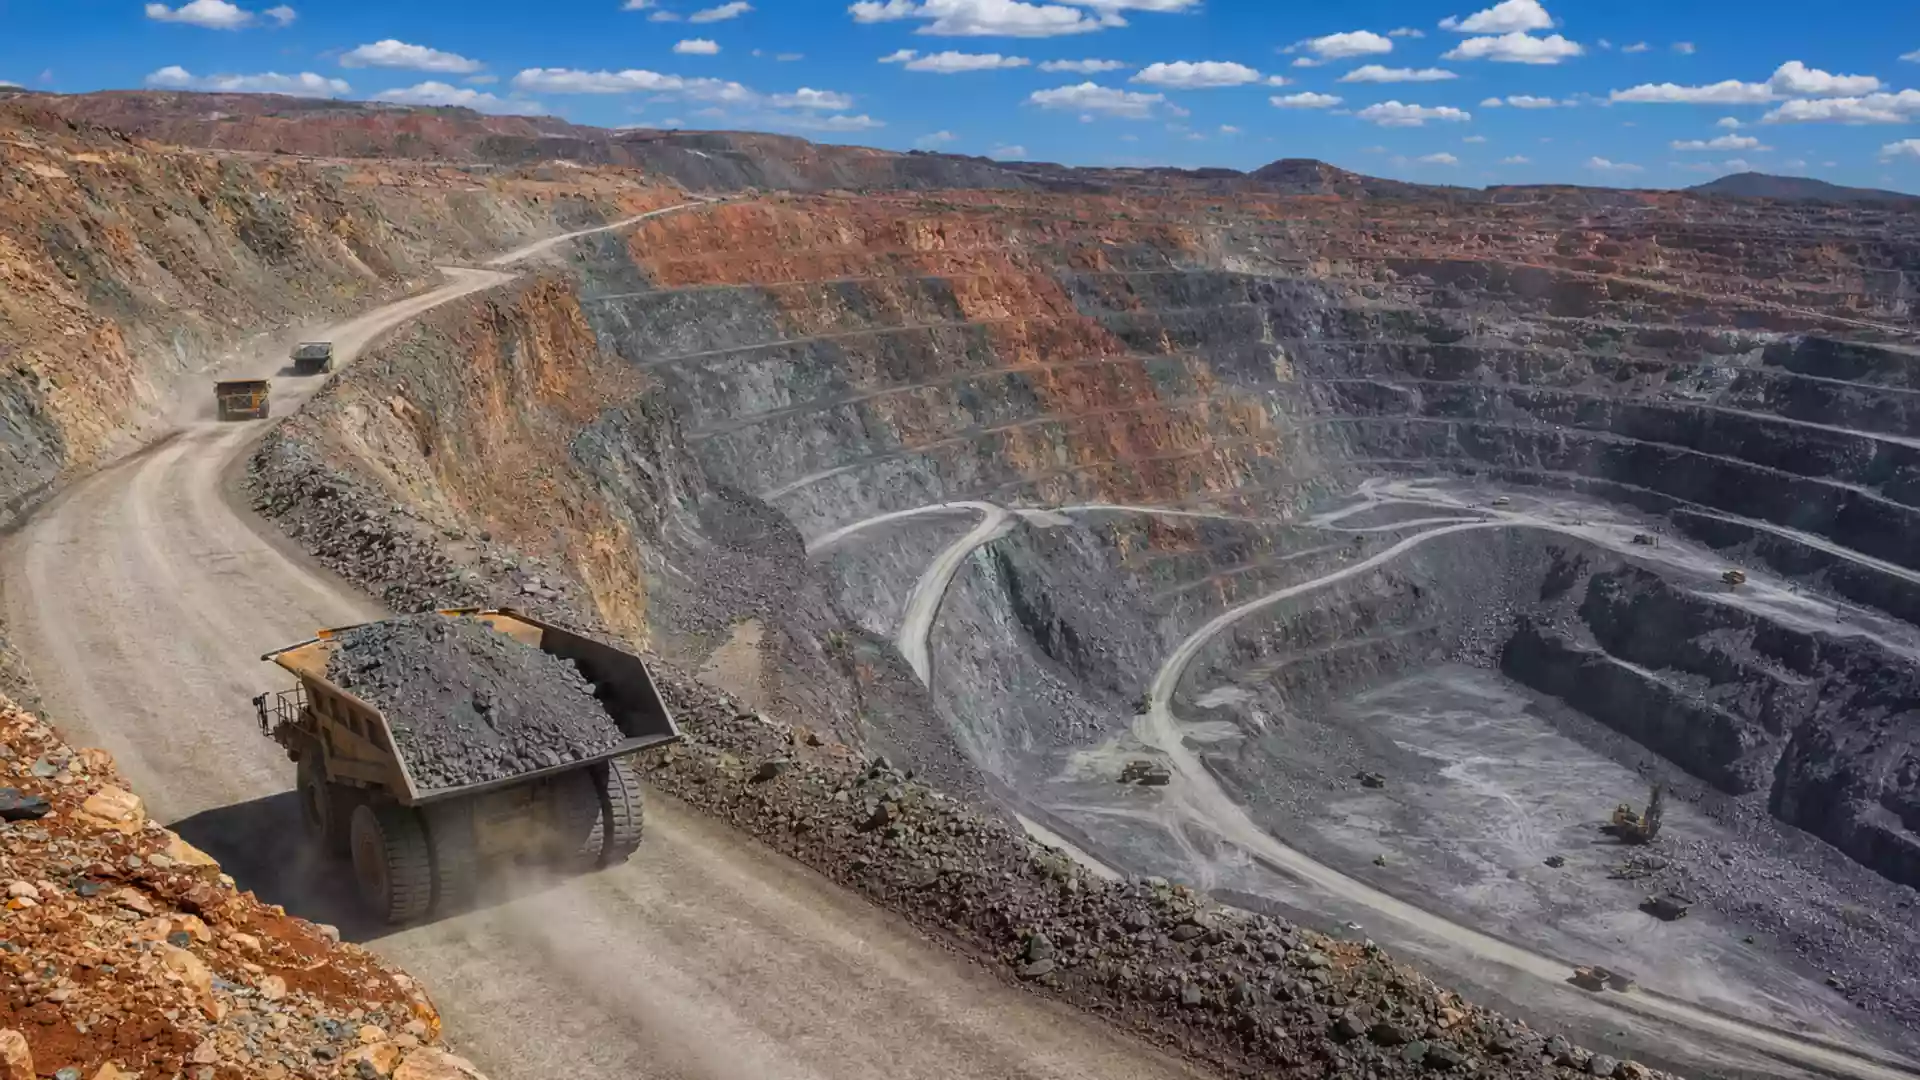
The company said Thursday that Sangdong produced tungsten concentrate for the first time in September, and that the first shipping container was loaded in Busan after the quarter closed. Those are genuine operational milestones. Whether they translate into durable earnings is a separate matter, and it is the one investors now have to underwrite.
A C$41.9 Million Top Line, a C$47.9 Million Paper Gain
Third-quarter 2026 revenue reached C$41.9 million, up 382% year over year — a step change in scale that reflects the ramp-up finally reaching the income statement. The net profit line showed C$50.2 million. Buried inside it were C$47.9 million of non-cash gains from the revaluation of derivatives and warrant instruments. Adjusted EBITDA came in at C$14.6 million.
Strip out the revaluation and the picture is a company whose operating result is still catching up with its revenue. That is not unusual for a producer in its first quarters of output, but it does mean the headline number flatters the business. The test ahead is whether Sangdong can convert technical milestones into recurring operating profit — the metric that ultimately anchors any valuation.
Should investors sell immediately? Or is it worth buying Almonty?
Two Analysts, One Direction of Travel
The sell-side response has been split in emphasis rather than in conviction. Stifel's Brock Cannon reiterated his Buy rating on Thursday while cutting his price target to US$18 from US$21, citing updated estimates and a lower valuation multiple following the quarterly report. Higher costs across the tungsten business were the stated concern.
Alliance Global took the opposite tack on the same day's weakness, calling the pullback a buying opportunity and reaffirming both its Buy rating and a US$26.25 target. Its case rests on Sangdong contributing more meaningfully to production and cash flow from the first quarter of 2027. The firm also noted that the recently reported results came in slightly below expectations while the ramp-up continues.
Both houses remain constructive; they simply weight the risks differently. One leans on the opportunity created by the share-price dip, the other on what cost inflation could do to the multiple. Neither has walked away.
The Conditions Behind the Bull Case
The valuation published Friday makes the prerequisites explicit: a Sangdong ramp-up that stays on schedule, plus progress on the expansion and the oxide plant. Delays or permitting hurdles would put that thesis under pressure. More than 90% of first-phase production is locked into long-term contracts, which gives the ramp a sales floor — but how much Almonty actually captures still depends on throughput and cost control.
The second expansion phase is slated for completion in 2027, contingent on first-phase performance and market conditions. The first quarter of 2027 is the next concrete checkpoint, when Alliance Global expects Sangdong's contribution to step up.
Almonty at a turning point? This analysis reveals what investors need to know now.
A US$67 Million Claim Sitting Alongside the Growth Story
Adding to the risk ledger is a legal dispute. Deutsche Rohstoff disclosed on Wednesday that it puts its claims against Almonty at roughly US$67 million. According to the company, its own suit and a separate Almonty action have been consolidated; the claims have not been established by any court.
That contingency belongs in any assessment of the equity while the asserted claims remain in dispute. For now, the investment case rests on a single condition: the production progress at Sangdong has to be carried by repeatable operating earnings. Until that link is proven, the growth story is a promise rather than a record.
Ad
Almonty Stock: New Analysis - 14 November
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.