

Almonty: A Restarted Mine, a Cooling Tungsten Price, and Three Dates That Will Decide the Story
Published on 10/17/2026 at 15:31 | Editorial boerse-global.de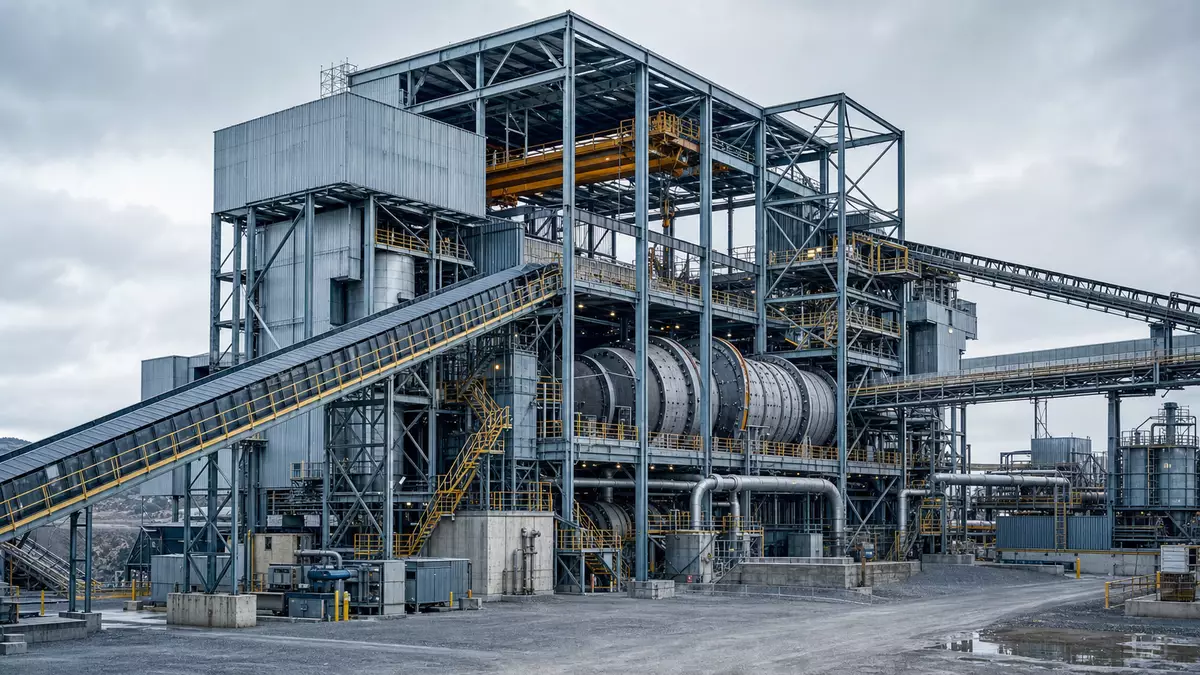
Almonty investors are being asked to weigh two things that rarely arrive together: genuine operational progress and a market that is turning less friendly. The company has restarted tungsten production at Sangdong for the first time since 1993, a milestone reached in late September and reported by trade media on 10 October. Yet the metal itself is getting cheaper, and the yardstick against which the stock is measured has just been shortened.
The share slipped 2.7% on Friday, though neither source of pressure can be tied directly to that move. What matters more is the calendar ahead: an investor day on 19 October 2026, a first commercial shipment from Sangdong targeted for 24 October, and monthly deliveries out of Rwanda pencilled in from November at more than 100 tonnes.
The price signal is real, but it is not a revenue line
Trade reports on Thursday put the reference price for 65%-grade wolframite concentrate at 302,000 yuan per standard tonne, down 75,000 yuan per standard tonne within the month. Industry outlets also flagged seasonally weak demand from downstream buyers and thin trading activity. For shareholders, that is a warning worth heeding — but it says nothing directly about what Almonty will book on its own sales. A production milestone and its financial effect are separate questions, and the benchmark price frames the debate without settling it.
Oppenheimer's Ian Zaffino made a related but distinct point on Thursday, trimming his price target to US$19 from US$25 while keeping an "Outperform" rating. The cut rested on lower valuation multiples among comparable companies, not on the tungsten price slide. Keeping those two headwinds apart matters: a positive analyst view does not inoculate a stock against a cheaper peer group, and a softer metal price is not the same thing as a downgrade.
Should investors sell immediately? Or is it worth buying Almonty?
What has actually been achieved
The Sangdong restart is the concrete item on the board. CEO Lewis Black, in a newsletter on the ramp-up roughly two weeks ago, pointed to 24 October for the first commercial delivery. On Rwanda, he reported that collection of tungsten material is already under way, with shipments of more than 100 tonnes per month planned from November.
Those two projects carry different weight. Sangdong represents a single, planned first shipment — a milestone. Rwanda points to a recurring monthly volume — a rhythm. Treating them as equivalent blurs the line between one delivery and a repeatable process. The real test is not only whether a date is met, but whether Almonty can then say something credible about what follows.
The optimistic path
Should the company deliver on schedule and explain its next steps clearly, the Sangdong shipment would mark tangible progress and regular Rwandan volumes would show that activity there goes beyond stockpiling material. That would not offset lower peer multiples by itself. It would, however, give investors a firmer basis for setting operational prospects against valuation risk — two things that would then have to be judged on their own terms.
The 19 October investor day, a live webcast covering the tungsten market, pricing and mine-by-mine operations, is where that case could be made. A convincing outlook would still be a promise rather than a delivery; its value would lie in making the next steps legible, with execution left to confirm whether the expectations were sound.
The risk that progress gets drowned out
The bear case is not simply delay. Even shipments that arrive on time could do little for the stock if investors keep granting lower valuations to comparable companies. That is precisely what the target cut signals: operational advances and a shrinking multiple are not mutually exclusive. Add the pricing backdrop — the analyst's reference to softening tungsten and APT prices at $2,700 per MTU — and volume alone cannot carry the valuation. Nor can that market price be read straight across into Almonty's own revenues or earnings power.
Almonty at a turning point? This analysis reveals what investors need to know now.
If deliveries slip or the intended cadence fails to materialise, the constructive reading weakens further, forcing a more cautious view on both execution and the assumptions underpinning the multiple.
Three checkpoints, not one verdict
The sequence gives shareholders several tests rather than a single decision day. First the investor day on 19 October, then the Sangdong first shipment on 24 October, then the Rwandan monthly volumes from November. Announcements and completions should be kept strictly apart throughout. What would justify a re-rating is not bolder language but delivery plans executed in a way investors can trace — and, on current evidence, that is the only thing that would let the operational story outshine a cooling metal price.
Ad
Almonty Stock: New Analysis - 17 October
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


