Aixtron's Order Book Doubles on AI Optics, but Twelve-Month Lead Times Set the Pace
Published on 10/31/2026 at 00:40 | Editorial boerse-global.de
Aixtron's problem is no longer a shortage of buyers. It is a shortage of finished machines. Orders for the German deposition-equipment maker's tools have surged on demand tied to AI data centres, yet the gap between signing a contract and shipping a system has stretched to roughly twelve months — and that gap, rather than the order intake itself, is what analysts and investors are now watching.
The scale of the demand became clear with third-quarter 2026 figures: order intake reached EUR 274.9m, up 122% year on year. Optoelectronics accounted for about 68% of equipment orders, with power electronics contributing 24%. Alongside the optical strength, a recovery in power semiconductors is gaining traction — and, according to Deutsche Bank Research, arriving sooner than expected.
Upgrades Arrive, Targets Come Down
Deutsche Bank Research raised its rating on the stock from "Hold" to "Buy" on the same day, while trimming its price target to EUR 42 from EUR 44. Analyst Michael Kuhn pointed to the sustained positive trend in optoelectronic systems and the earlier-than-anticipated rebound in power chips. The pairing is instructive: a brighter view of the business does not automatically translate into a richer valuation, and the recovery story and the share price remain two separate questions.
Jefferies had confirmed its own Buy rating with a EUR 44 target a day earlier. Analyst Om Bakhda highlighted accelerating order momentum in equipment for silicon carbide and gallium nitride chips. Mwb research likewise reiterated its Buy recommendation with a EUR 45 target, citing an upturn in gallium nitride that adds a further impulse alongside the optical demand.
Should investors sell immediately? Or is it worth buying Aixtron?
A Sector Selloff, Not a Company Verdict
None of that shielded the shares from the wider market. Aixtron traded down 4.1% on the day, with dpa-AFX attributing the pressure on the technology sector to disappointing figures and guidance from Amazon and Intel. Reuters, meanwhile, reported on Intel's weak outlook and renewed doubts about the returns on heavy AI investment — a theme that rippled through European chip names, Aixtron among them.
Distinguishing between a sector-wide de-rating and Aixtron's own operating trajectory matters here. A broad selloff can hit a range of companies at once without their order books moving in the same direction. Reading a single day's loss as evidence of an operational reversal would be a mistake; reading only the upgrade and ignoring the climate would be one too.
The Bottleneck Moves to the Factory Floor
What actually determines the pace from here is the production ramp. Mwb research noted that delivery times have lengthened to around twelve months, and management has guided toward at least continued high order intake for a further two to three quarters. Additional bookings retain their value, but revenue growth now hinges on when Aixtron can physically deliver its systems — a full order backlog does not answer that question on its own.
The company confirmed its 2026 revenue guidance of EUR 560m ±30m, meaning the order surge has so far not lifted the top-line forecast. Management expects 2027 to be a solid growth year driven by optoelectronics, but that is an expectation rather than a delivered result: it presupposes that demand and delivery capacity meet.
A 48% Margin That May Not Repeat
Execution is not the only caveat. Gross margin reached 48% in the third quarter, and mwb research considers a repeat unlikely in the following quarter given a less favourable product and regional mix — prompting the house to withdraw its recent upward revision to its gross-margin forecast. A particularly profitable quarter, in other words, is not a durable yardstick, and rising revenue need not flow through to earnings in the same proportion. What Aixtron ships, and where it sells it, will decide that.
Aixtron at a turning point? This analysis reveals what investors need to know now.
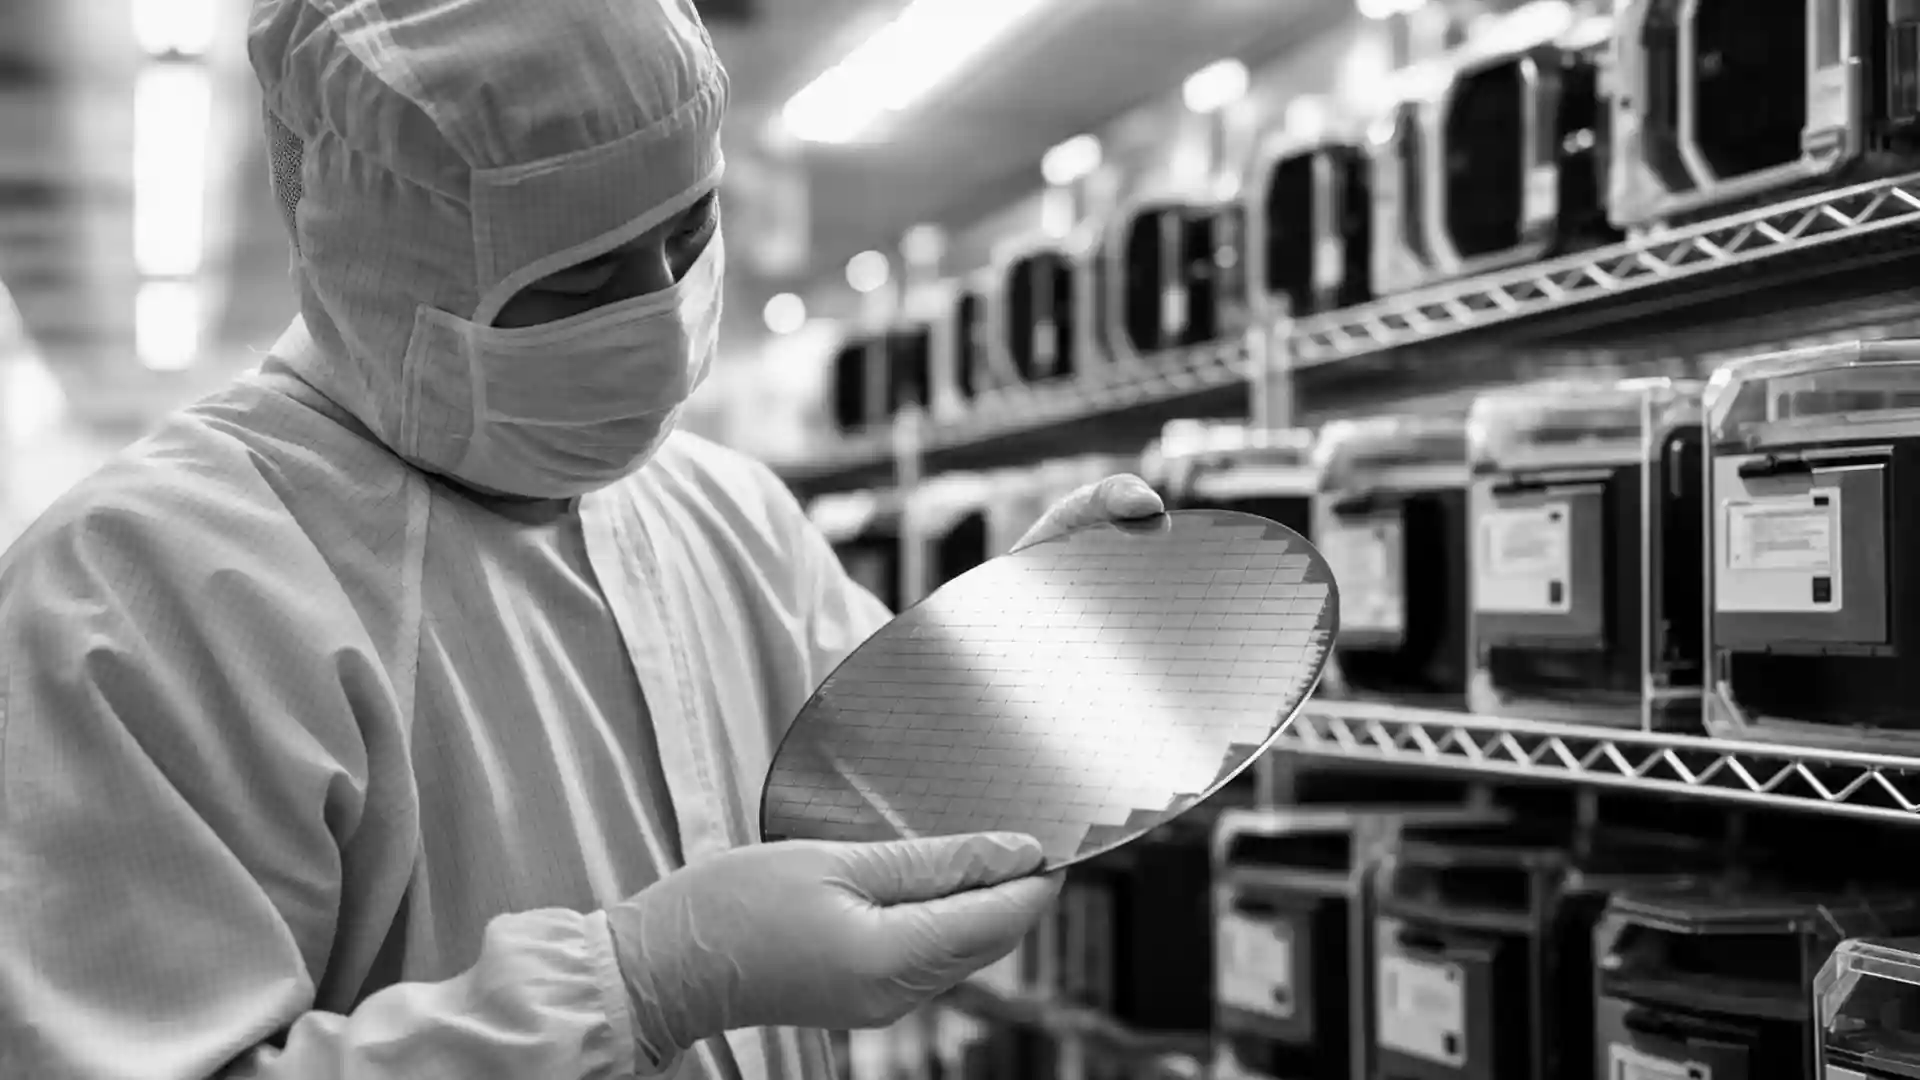
Material availability adds a further constraint: mwb research flags limited supply of larger indium phosphide substrates as a brake on the shift to bigger wafers. Progress therefore depends on more than demand alone — production changeovers and input availability can both slow the pace.
The next checkpoint comes on 1 December, when Aixtron is scheduled to appear at the German Select IX Conference. No new guidance has been announced for the event. Investors will be listening for firmer detail on lead times, capacity and the durability of demand — evidence that the path from order to shipment is being backed with substance rather than another expression of confidence in the order book.
Ad
Aixtron Stock: New Analysis - 31 October
Fresh Aixtron information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.