Synopsys stock: S&P lifts rating as AI growth outlook strengthens
Published on 11/04/2026 at 15:17 | Editorial responsibility: Rafael Müller, Editor-in-Chief AD HOC NEWSRating Upgrade Lifts Long-Term View
- S&P expects Synopsys revenue growth in 2027 through 2029 to reach the mid-teens percentage range.
- The agency projects a 49 percent EBITDA margin for 2029, up from its prior 45 percent forecast.
- Ansys cost synergies are expected to reach 400 million US dollars by fiscal 2027, one year ahead of schedule.

Synopsys stock is in focus after S&P Global Ratings raised the company’s issuer credit rating to BBB+ from BBB on October 26, 2026, while keeping the outlook stable. In its research update, the agency cited stronger long-term operating expectations after Synopsys presented new guidance at its analyst day.
S&P lifted its annual revenue growth expectations for 2027 through 2029 to the mid-teens percentage range from about 10 percent. The agency also raised its 2029 EBITDA margin forecast to 49 percent from 45 percent. Synopsys management is targeting roughly 15 percent annual revenue growth through 2030 and operating margins near 50 percent.
AI Demand Supports EDA Expansion
The rating analysis treats artificial intelligence as a potential demand accelerator rather than only a competitive threat. S&P said AI-driven design can increase the number of design iterations, verification runs and simulations, which may raise consumption of Synopsys tools. The agency also pointed to new AI offerings and the company’s OpenAI partnership as potential monetization channels.
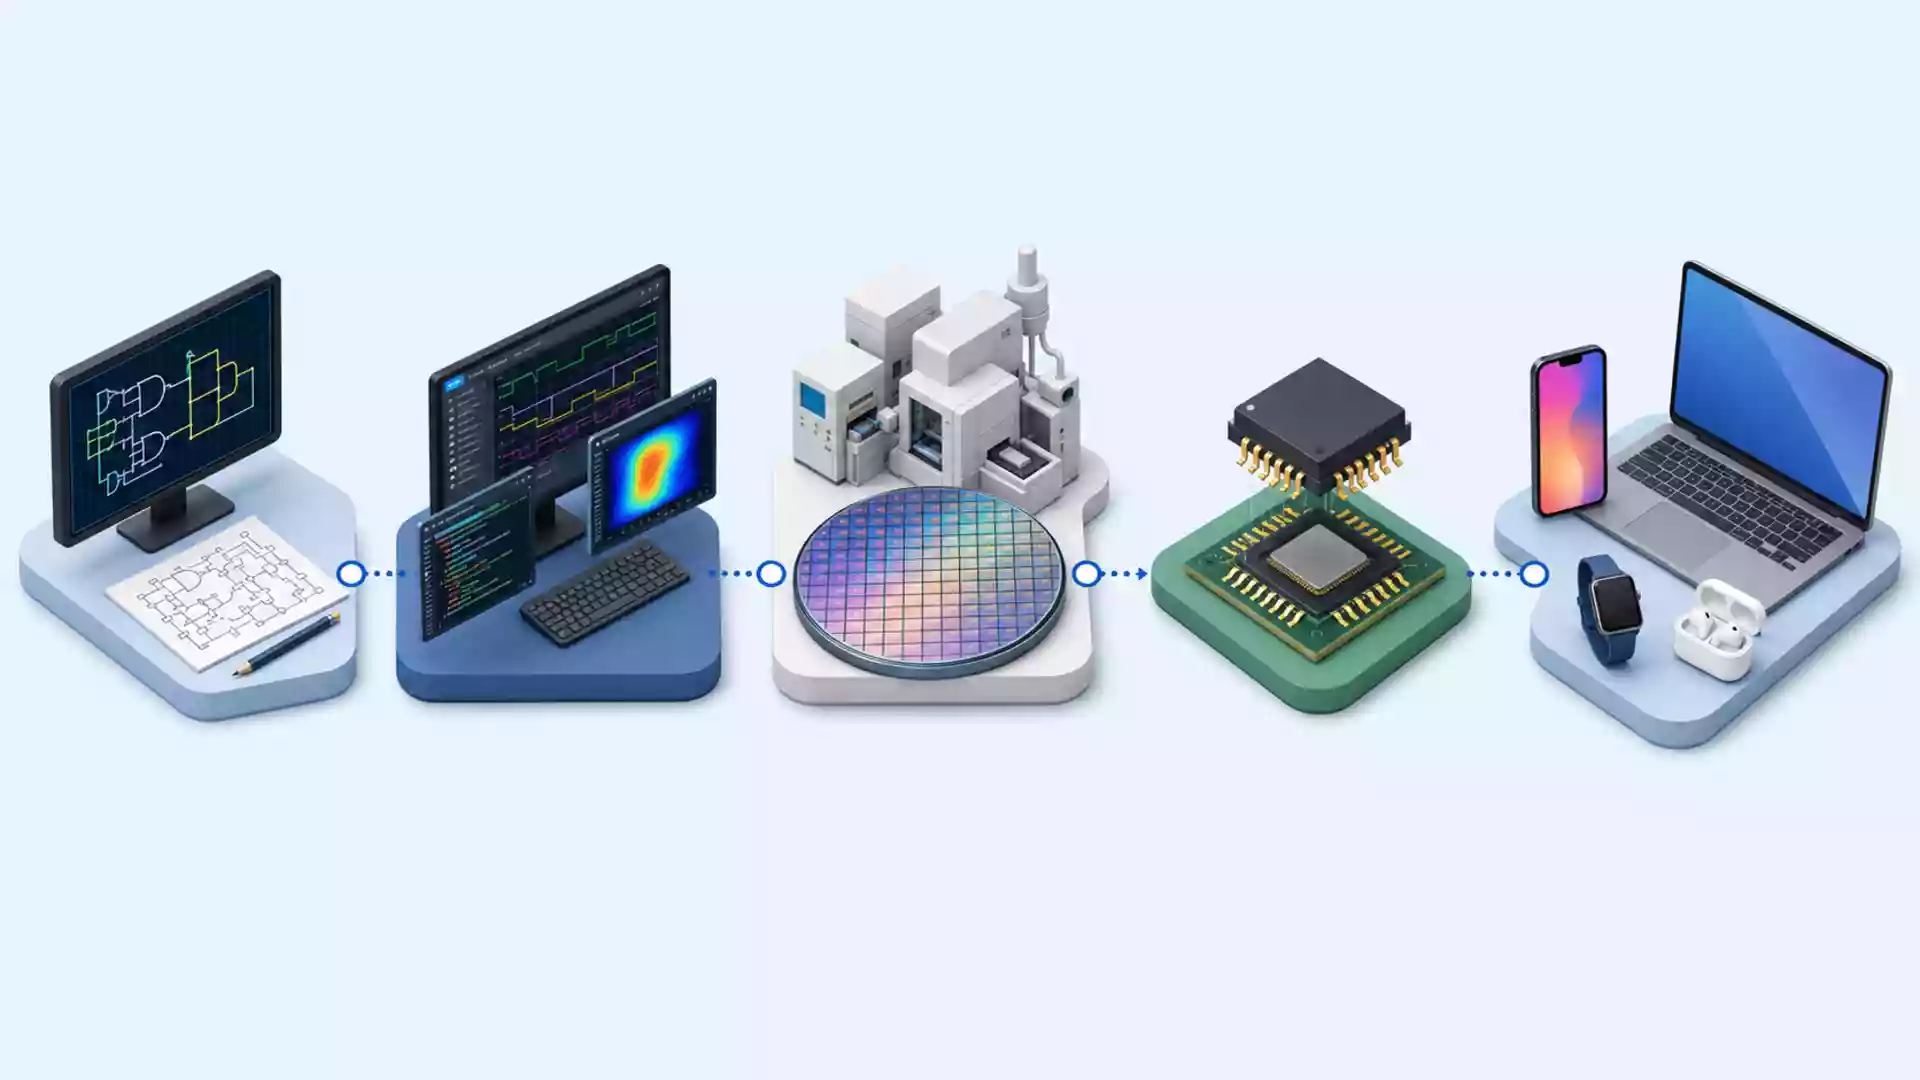
Synopsys combines electronic design automation, semiconductor intellectual property and simulation software in its silicon-to-systems strategy. That positioning is intended to address rising engineering complexity as customers develop advanced chips, multi-die systems and AI infrastructure.
Ansys Integration Remains Central
The integration of Ansys is ahead of schedule in S&P’s assessment. Cost synergies are expected to reach 400 million US dollars by fiscal 2027, one year earlier than previously planned. The agency said revenue synergies, AI monetization, higher-margin software and royalty income provide additional routes to stronger growth and margins.
S&P nevertheless identified risks for investors. A large acquisition with limited EBITDA could weaken credit metrics, while faster displacement by AI or open-source electronic design automation tools could pressure the rating. The agency said an upgrade could become possible if Synopsys sustains leverage below 2 times, while leverage above 2.5 times could trigger a downgrade.
Synopsys stock traded at 410.50 euros on Lang & Schwarz at 15:06 CET on Wednesday, November 4, 2026, 0.24 percent below the Xetra close of Tuesday, November 3, 2026 at 411.50 euros. The real-time quote of Synopsys stock reflects the current euro listing, while S&P’s rating action addresses the company’s credit profile rather than a short-term price target.
Synopsys Inc. stock facts
- Company: Synopsys Inc.
- ISIN: US8716071076
- Ticker: SNPS
- Home exchange: Nasdaq
- Lang & Schwarz quote: 410.50 euros at 15:06 CET on November 4, 2026
- Change versus Xetra: 0.24 percent below the November 3, 2026 close
- Xetra close: 411.50 euros on November 3, 2026
- Sector: Technology services
The broader US equity backdrop is covered in current market reports.
More news and analyses on Synopsys stock will follow as the company provides further detail on AI adoption, Ansys integration and its long-term financial targets.