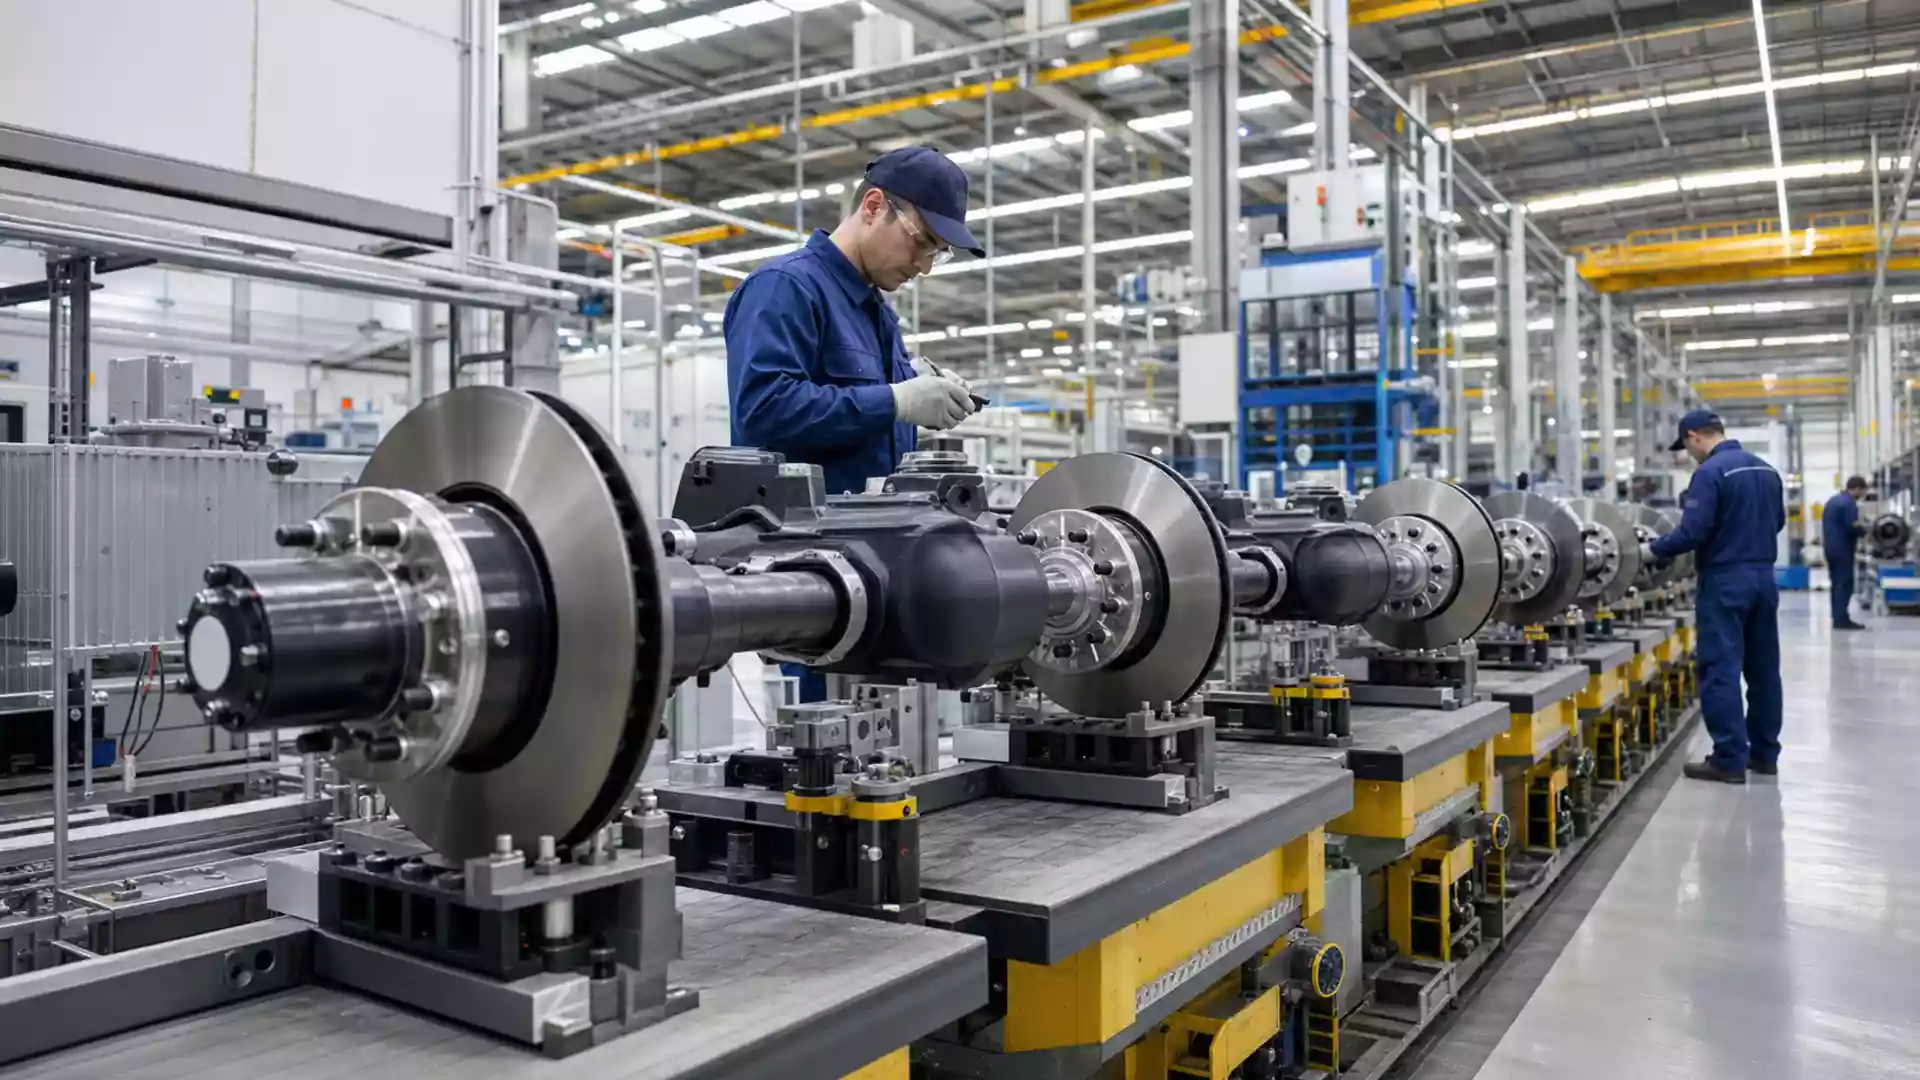
Knorr-Bremse stock weighs strong Q3 against weaker Rail orders
Published on 11/13/2026 at 11:54 | Editorial responsibility: Rafael Müller, Editor-in-Chief AD HOC NEWSStrong quarter, uneven order trends
- Knorr-Bremse reported resilient third-quarter profitability and higher group order intake.
- Rail orders trailed expectations after customer postponements and a European project was not pursued for profitability reasons.
- Management expects revenue and free cash flow at the upper ends of their 2026 guidance ranges.
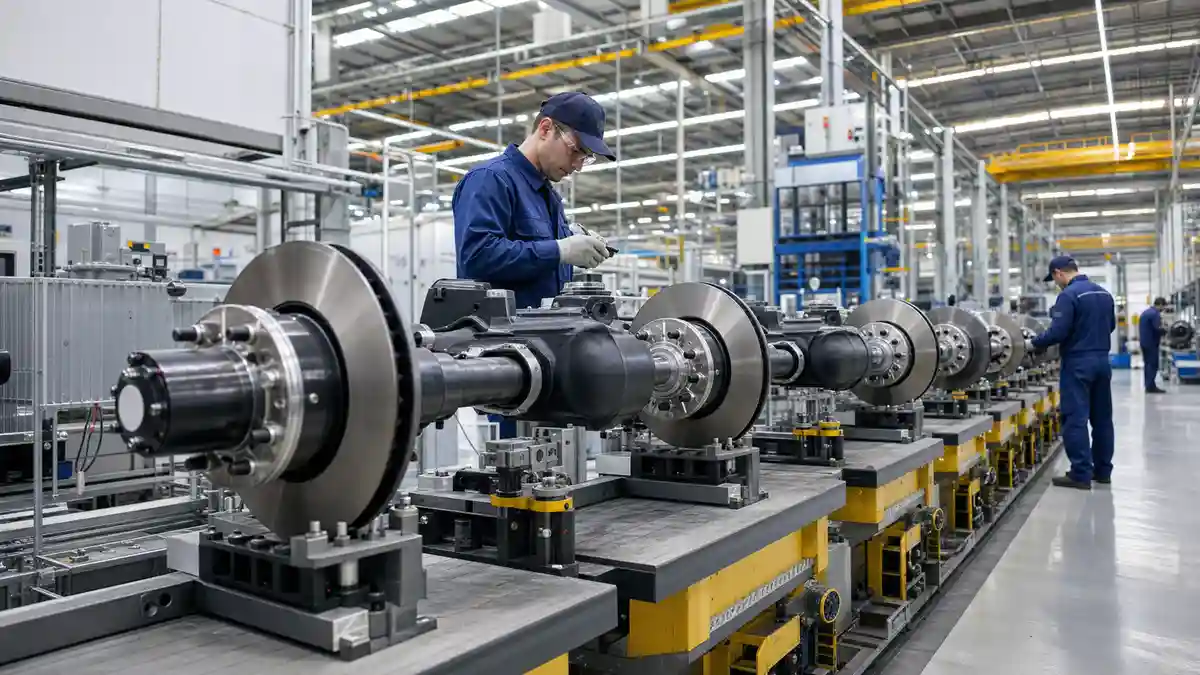
Knorr-Bremse reported a solid third quarter on October 28, 2026, but the figures carried a clear split between resilient profitability and weaker Rail order intake. In its investor-relations release, the company said revenue and free cash flow should reach the upper ends of their 2026 guidance ranges.
Group order intake came to about 2.05 billion euros in the July-to-September period, below the Vara Research consensus of 2.16 billion euros. The Rail Division contributed about 1.05 billion euros, compared with a consensus estimate of 1.18 billion euros, while Truck Division order intake reached about 1.02 billion euros against expectations of 0.99 billion euros.
Rail weakness meets strong profitability
Knorr-Bremse attributed the Rail shortfall mainly to customer orders worth around 80 million euros that were postponed. The company expects those orders to be awarded within six months. It also chose not to actively pursue a European project because management considered the profitability insufficient.
Management expects a partial catch-up in the fourth quarter, with Rail order intake again targeted at about 1.2 billion euros. That outlook keeps the focus on execution in the project-driven Rail business, where individual awards can shift quarterly order intake without necessarily changing the longer-term demand picture.
Other Q3 indicators were stronger. Free cash flow reached about 238 million euros, up from 159 million euros a year earlier. Revenue was about 2.05 billion euros, operating EBIT about 299 million euros and the operating EBIT margin about 14.6 percent. Earnings per share came to 1.09 euros, below the Vara consensus of 1.17 euros.
Guidance remains at the upper end
Knorr-Bremse confirmed its 2026 revenue guidance of 8.1 billion to 8.3 billion euros, an operating EBIT margin of 14.0 percent to 14.5 percent and free cash flow of 750 million to 850 million euros. Management expects both revenue and free cash flow at the upper ends of those ranges. The outlook depends on broadly stable geopolitical and macroeconomic conditions, current foreign-exchange rates and no major tariff effects.
For investors, the quarterly picture therefore rests on two opposing signals: Truck order momentum exceeded the cited consensus, while Rail intake missed expectations and remains dependent on delayed customer awards. The high-margin profile and firm cash-flow outlook provide support, but the fourth-quarter Rail recovery is the next operational milestone.
Knorr-Bremse stock traded at 99.00 euros on Lang & Schwarz at 11:49 CET on Friday, November 13, 0.05 percent below the Xetra close of Thursday, November 12.
Knorr-Bremse AG at a glance
- Company: Knorr-Bremse Aktiengesellschaft
- ISIN: DE000KBX1006
- Ticker: KBX.DE
- Listing: Frankfurt Stock Exchange, Prime Standard
- Latest quote: 99.00 euros on Lang & Schwarz, Friday, November 13, 2026, 11:49 CET
- Daily comparison: 0.05 percent below the Xetra close of Thursday, November 12, 2026
- Index: MDAX
German industrial investors are also watching the DAX as earnings trends and economic expectations shape the broader market backdrop. Further market context is available in Current market reports.
More company-specific developments can be found in More news and analyses on Knorr-Bremse stock.