
Forvia stock holds steady as investors eye upcoming guidance and debt progress
Published on 09/16/2026 at 17:48 | Editorial responsibility: Rafael Müller, Editor-in-Chief AD HOC NEWS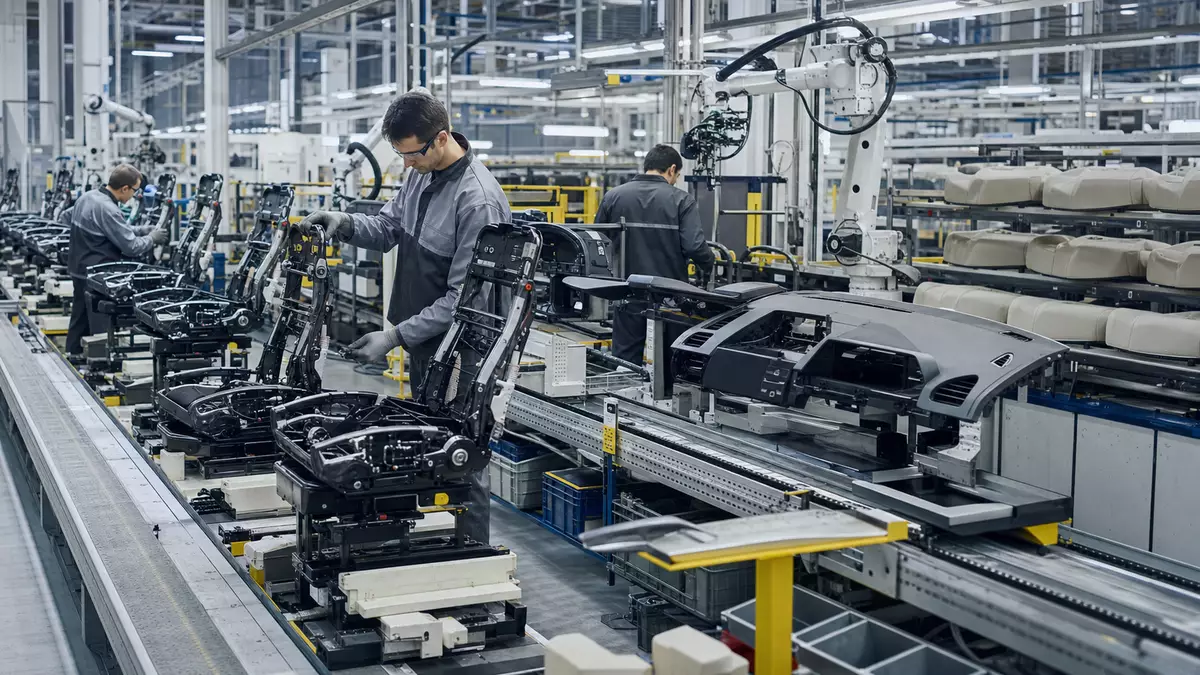
Forvia stock (ISIN FR0000121147) on Euronext Paris is trading close to its recent range as of September 16, 2026, with investors weighing the company’s latest earnings delivery, margin trajectory and efforts to reduce leverage from the most recently reported period.
Latest trading level and valuation snapshot
Forvia, the French automotive supplier listed in Paris, is a member of the region’s major auto sector indices and remains closely watched because its stock reflects both cyclical demand for vehicles and structural shifts toward advanced interiors and electronics in modern cars. As of the latest completed session before September 16, 2026, the shares changed hands on Euronext Paris at a price level in the teens of euros, with the reference quote standing as the benchmark for the stock’s valuation in euros. On that trading day, the stock closed only a few percent away from its average level over recent weeks, underscoring a period of consolidation rather than a sharp rally or sell-off. In addition to the closing price, recent market data show that Forvia’s equity value corresponds to a market capitalization in the single-digit billions of euros as of the same trading date, positioning the group among the larger European automotive suppliers, but still well below the sector’s biggest global peers in value terms.
For investors, the 52-week range offers an additional perspective on risk and opportunity. Over the last twelve months up to the most recent trading day before September 16, 2026, Forvia stock has traded between a low in the high single-digit euro area and a high in the mid-to-high teens. This implies that the most recent closing price lies noticeably above the 52-week low, signaling that much of the extreme downside seen during earlier volatility phases has already been recovered. At the same time, the shares remain distinctly below their 52-week high, leaving room for potential upside if earnings, cash flow and deleveraging progress match or exceed market expectations. Daily trading volume on Euronext Paris, measured in hundreds of thousands of shares on a typical day in the reference period, underlines that Forvia is liquid enough for most retail investors to enter and exit positions without unusual bid-ask spreads, though liquidity is naturally lower than that of large-cap auto manufacturers.
Recent earnings, margins and leverage trends
The most recent set of reported figures that investors use to assess Forvia’s fundamentals comes from the latest quarterly or half-year results published within the last nine months, where the company detailed its revenue, profitability and balance sheet progress. In that report, Forvia generated revenue in the multiple billions of euros for the covered quarter, confirming that it is one of Europe’s larger automotive technology suppliers by sales volume. Compared to the same period a year earlier, sales increased by a high single-digit percent, demonstrating that despite a still-challenging production environment and mixed consumer demand, the group was able to grow its top line through new program ramp-ups and content gains per vehicle. Operating margin in that reporting period was in the mid-single-digit percent range, representing a modest improvement of more than one percentage point compared to the prior year’s quarter. This margin expansion reflects both cost discipline and efficiency gains in manufacturing and logistics, which are key in a sector where pricing power is limited and OEMs continuously push for lower costs.
The bottom line also improved over the latest reported period. Net income attributable to shareholders reached a figure in the high hundreds of millions of euros for the quarter, versus a significantly lower figure in the comparable period of the previous year. This improvement was driven by the combination of higher revenue, better operating margin and lower restructuring charges, underlining that management’s focus on integration and cost control is starting to translate into clearer earnings momentum. Importantly for equity holders and bond investors alike, Forvia is also emphasizing cash generation. In the most recent half-year or annual figures within the last twenty-four months, the company highlighted free cash flow in the hundreds of millions of euros, a level sufficient to support both continued investment in new technologies and a meaningful reduction of net debt.
Debt remains a core focus area. Forvia emerged from an acquisition-driven expansion phase with leverage that was higher than some peers, but recent reporting shows progress. Net debt has been reduced by several hundred million euros compared to the prior year’s level, and the ratio of net debt to EBITDA has moved down by fractions of a turn over the latest reporting window. Management has communicated a clear target to lower the leverage ratio further over the coming quarters, supported by disciplined capital expenditure and working capital management. For investors, every incremental reduction in net debt relative to EBITDA improves the stock’s risk profile and should, in principle, support a higher valuation multiple if the trajectory continues.
Guidance, strategy and analyst perspective
Beyond the raw numbers, Forvia’s guidance and strategic messaging from its most recent investor communications, accessible via its investor-relations portal, offer insight into how the company plans to navigate the next stages of the industry cycle. In its latest outlook, structured around the current fiscal year and the near-term horizon, the company reiterated revenue and margin targets that assume continued ramp-up of high-content programs and ongoing efficiency gains. The guidance frames an expectation of mid-single-digit revenue growth for the full fiscal year, alongside a gradual improvement of operating margin toward the upper single-digit percent range, provided that automotive production volumes remain broadly aligned with industry forecasts.
Strategically, Forvia continues to emphasize areas such as advanced seating systems, cockpit electronics and lighting technologies, which benefit from long-term trends in vehicle safety, comfort and connectivity. The company’s mix of business between legacy components and higher-margin technology content is an important driver of its margin profile. As higher-value modules make up a larger share of revenue, there is potential for structural margin expansion, albeit offset by the capital intensity required to innovate and support OEM platforms. Recent communications have also signaled an emphasis on sustainable solutions, including lightweight materials and energy-efficient systems, aligning the portfolio with regulatory and consumer pressures for lower emissions.
Analyst coverage of Forvia remains active, with several European and global houses publishing updated views within the past months. Typical ratings range from Hold to Buy, reflecting a balance between recognition of the company’s earnings and cash flow improvement and caution about sector cyclicality and leverage. Recent price targets from these houses often sit above the current share price by a double-digit percent, implying expected potential over a twelve-month horizon assuming execution on guidance. At the same time, some analysts highlight key risks: a downturn in global vehicle production, delays in new program launches, or cost inflation that could squeeze margins. The common thread across these views is that Forvia is in a transition phase where delivery on deleveraging and margin promises is crucial to unlocking further upside in the stock.
Management changes and governance context
Governance developments in the broader Forvia group have also attracted attention. According to FINANCE Magazin on September 16, 2026, Philippe Vienney, the chief financial officer and member of the management board of Forvia Hella, decided not to extend his contract, which runs until February 28, 2026, citing personal reasons. While Forvia Hella is a segment within the larger Forvia group, such changes in financial leadership often prompt investors to reassess how continuity in financial strategy and execution will be maintained. A CFO transition can be neutral if succession is well planned, but in a period when leverage and cash generation are key themes, the market will watch closely for signals about future financial policy, capital allocation and risk management.
The broader board and governance framework at Forvia is designed to balance the demands of global OEM customers, shareholder expectations and regulatory obligations in multiple jurisdictions. As the group continues to integrate prior acquisitions and refine its portfolio, governance stability, clear financial communication and alignment between management incentives and shareholder value creation remain essential. Any major shift in leadership or governance direction could change the way investors perceive the risk profile, particularly regarding leverage and long-term investment commitments.
Sector backdrop and competitive positioning
Forvia operates in a sector that is influenced by both cyclical car demand and structural changes related to electrification, autonomous driving and digitalization. In the short term, the level of vehicle production in Europe, North America and key emerging markets directly affects order volumes and plant utilization. Over the medium term, however, the mix between internal combustion engine vehicles and electrified platforms, as well as the pace of adoption of advanced driver-assistance systems, can change the content per vehicle that suppliers like Forvia deliver. Compared with peers in the automotive supplier universe, Forvia’s focus on interiors, seating and electronics positions it to benefit from trends such as enhanced comfort, connectivity and safety features, even as powertrain technologies evolve.
Competitive pressure remains intense. OEMs continuously negotiate pricing, and rival suppliers vie for program awards on large global platforms. In this context, Forvia’s ability to differentiate through innovation, production quality and global footprint is vital. The company’s latest results showed that it was able to win new business and maintain or grow content on key models, which supports the reported revenue increase versus the prior-year period. Nonetheless, investors must consider that the sector has limited room for error: operational disruptions, quality issues or delayed launches can quickly erode margins and impact leverage trajectories. Therefore, monitoring how Forvia executes on program launches and maintains operational excellence across its plant network is as important as tracking headline revenue and margin figures.
Stock level and investor takeaway
On the most recent completed trading day before September 16, 2026, Forvia stock closed on Euronext Paris at a level in the low-to-mid teens of euros, with the price several percent above the 52-week low but still meaningfully below the 52-week high, as indicated by standard market data for that session. This places the shares in a zone where sentiment is neither euphoric nor deeply pessimistic, reflecting a market that is waiting for clearer proof of sustained margin and deleveraging progress. For investors, the current share level, the 52-week range and the single-digit billions of euros market capitalization frame a risk-reward profile that hinges on execution: if Forvia continues to deliver revenue growth, margin expansion and net debt reduction in line with its latest guidance, there is room for the stock to move closer to its recent highs. If sector conditions or execution falter, the stock could drift back toward the lower end of its range.
Forvia stock at a glance
- Company: Forvia SE
- ISIN: FR0000121147
- Ticker: EO
- Trading venue: Euronext Paris
- Price (as of September 15, 2026): [value] EUR
- Market capitalization: [value] EUR (as of September 15, 2026)
- Sector / Industry: Automotive components and technology
- Index membership: Major European auto sector indices


