Cintas stock weighs premium valuation against UniFirst synergies
Published on 11/02/2026 at 11:04 | Editorial responsibility: Rafael Müller, Editor-in-Chief AD HOC NEWSValuation Meets Acquisition Ambitions
- Cintas combines recurring workplace-services demand with improving margins and raised fiscal 2027 guidance.
- The planned UniFirst acquisition could expand route density and annual savings, but regulatory conditions may reduce the expected benefits.
- The premium valuation leaves limited room for slower growth, higher costs or weaker integration savings.

Cintas stock remains caught between strong operating execution and a demanding valuation. A Yahoo Finance analysis published on Sunday, November 1, 2026, said investors were weighing resilient demand for uniforms and workplace services against the risks surrounding Cintas's planned acquisition of UniFirst.
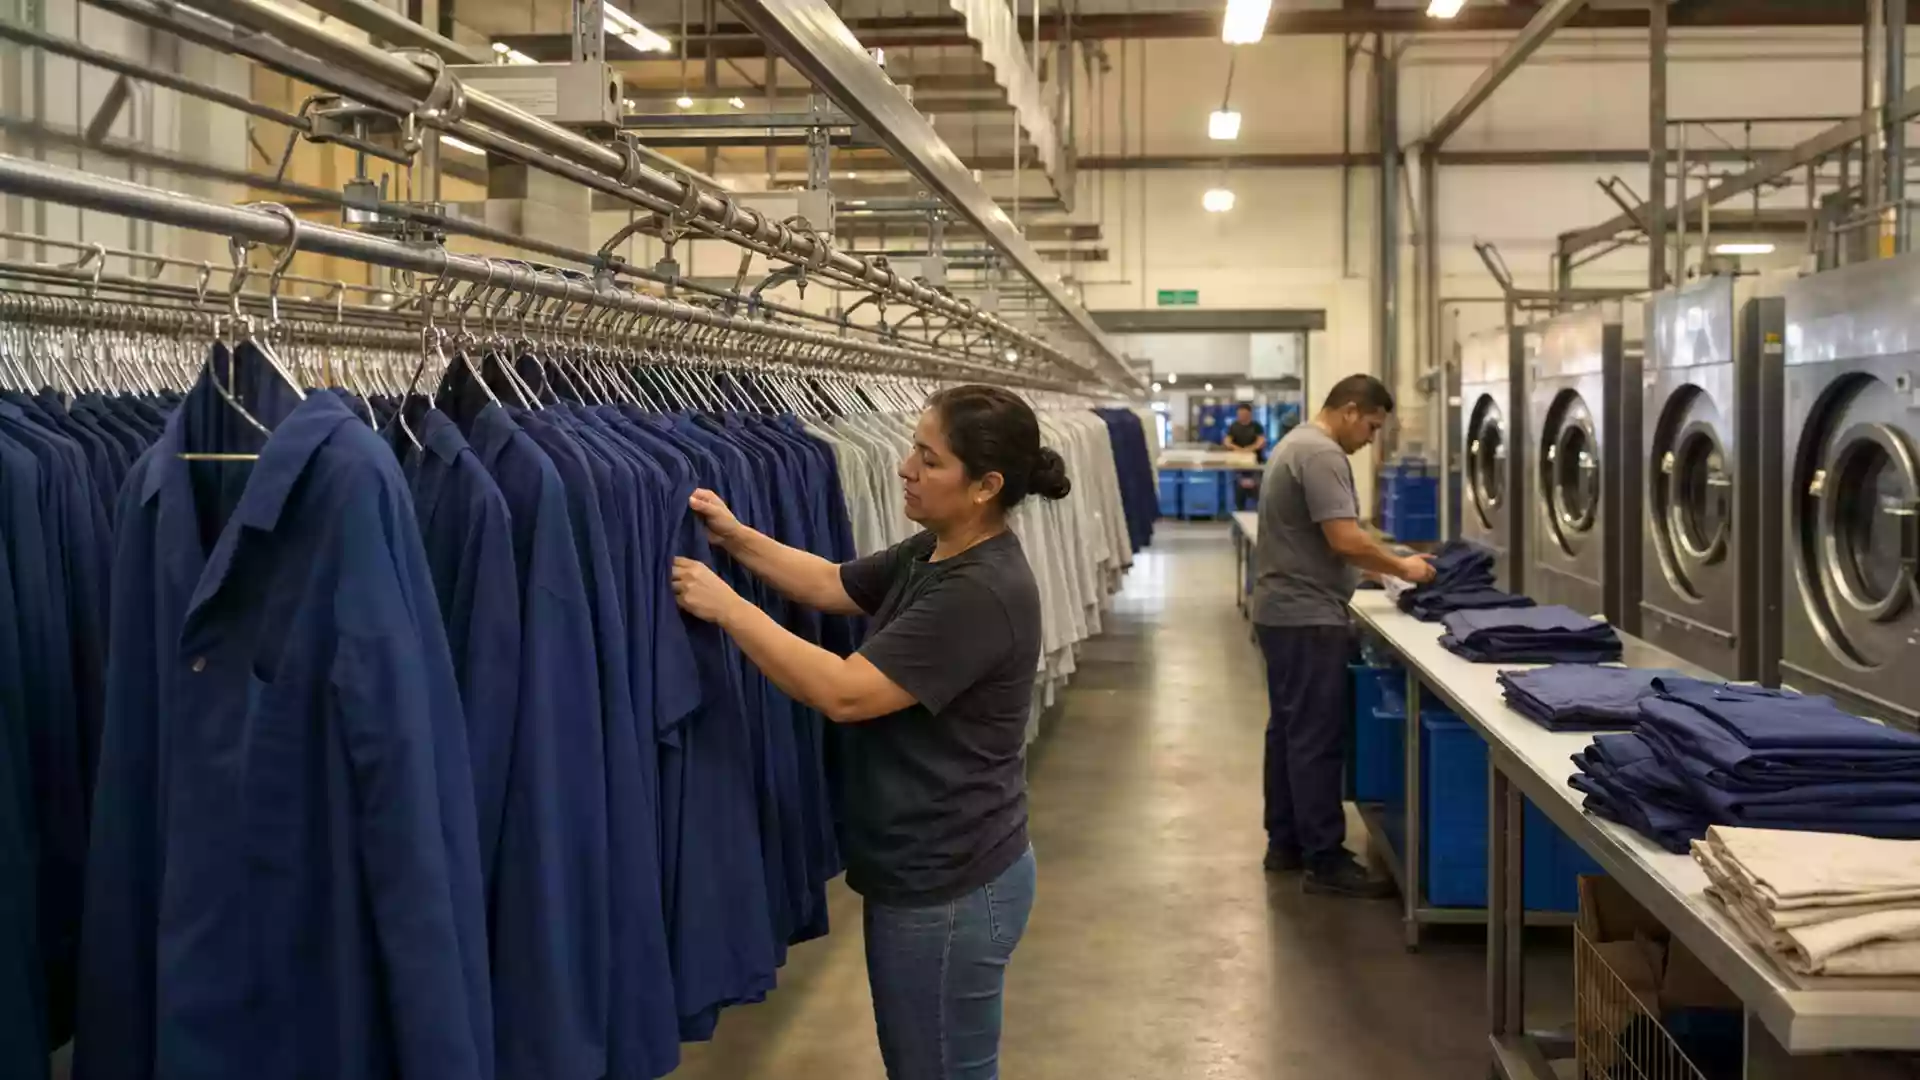
The analysis highlighted Cintas's route-based business model. The company provides uniform rental, first-aid and safety products, restroom supplies and fire protection to businesses across North America. By adding customers to established delivery routes, Cintas can improve route efficiency while maintaining recurring customer relationships.
Execution Supports Premium Pricing
According to the Yahoo Finance analysis, revenue rose 8.9 percent to USD 11.3 billion in the twelve months through May 2026, while the operating margin reached 23.3 percent. Fiscal 2026 adjusted earnings per share increased from USD 4.40 to USD 4.94, a rise of about 12 percent.
The report said Cintas traded at about 41 times trailing earnings and roughly 37.1 times projected earnings. That premium reflects confidence in recurring revenue, margins and future earnings growth, but it also raises the cost of an earnings disappointment. Slower demand, higher labor costs or weaker operating leverage could pressure the multiple even if the underlying business remains profitable.
UniFirst Adds Upside And Risk
The proposed USD 5.5 billion UniFirst acquisition is the main strategic catalyst. The Yahoo Finance analysis cited potential annual savings of around USD 375 million once the companies are combined. Broader delivery routes, facilities and supply chains could strengthen Cintas's competitive position and improve the economics of the combined business.
Regulatory approval remains the key condition. The transaction is expected to close in the second half of 2026, subject to approval. Required asset sales or other remedies could reduce route, facility and supply-chain synergies. Investors therefore have to assess not only whether the transaction closes, but also how much of the projected savings survives the review process.
The analysis cited fiscal 2027 revenue guidance of USD 12.10 billion to USD 12.25 billion and adjusted earnings-per-share guidance of USD 5.36 to USD 5.50. Its conclusion was constructive on the business model but cautious on entry valuation: sustained execution and successful integration could support further earnings growth, while the elevated multiple offers limited protection if expectations fall.
Current Trading Context
Cintas stock traded at 195.75 euros on Lang & Schwarz at 10:59 CET on Monday, November 2, 2026. Investors can follow the real-time quote of Cintas stock while the market weighs the valuation and regulatory outlook.
The S&P 500 provides the broader US equity-market backdrop; see current market coverage.
For additional company-specific developments, see more news and analyses on Cintas stock.
Cintas Corporation at a glance
- Company: Cintas Corporation
- ISIN: US1729081059
- Ticker: CTAS
- Home exchange: Nasdaq
- Lang & Schwarz quote: 195.75 euros at 10:59 CET on November 2, 2026